


Higher Oil, Higher Rates and Trade Uncertainty Weigh on Markets
Week Ending August 21, 2026
After a few relatively quiet summer weeks, investors had a little more to digest last week.
Markets moved lower as rising oil prices brought inflation concerns back into the conversation, bond yields climbed and Canada/U.S. trade negotiations added another layer of uncertainty closer to home.
None of these issues are particularly new.
What changed last week was that several of them showed up at the same time.
Higher oil prices can eventually make their way into everything from gasoline and airfare to the cost of transporting goods. That matters because just as central banks have been making progress getting inflation under control, higher energy prices have the potential to complicate things again.
Markets didn't love that combination.
Market Overview
Weekly Market Performance
- S&P 500: -1.43%
- Nasdaq Composite: -2.05%
- Dow Jones Industrial Average: -0.85%
- MSCI EAFE Index: -0.40%
- S&P/TSX Composite Index: approximately -0.3%
Technology stocks saw the biggest pullback, with the Nasdaq falling just over 2% for the week.
Canadian markets held up somewhat better, helped by our larger exposure to areas like energy and materials.
Friday did bring a bit of a rebound, but it wasn't enough to erase the losses from earlier in the week.
So, what was making investors nervous?
A big part of the answer comes back to interest rates.
Why Were Bond Yields Suddenly Such a Big Deal?
Bond yields aren't usually the most exciting thing to talk about, but last week they were difficult to ignore.
Government bond yields moved sharply higher around the world, with the yield on the 30 year U.S. Treasury reaching levels we haven't seen in nearly two decades.
Here's the simple version of why that matters.
When investors lend money to governments by buying bonds, they expect to receive a return. If they're worried about inflation, government debt or where the economy is heading, they may demand a higher return for lending that money.
That's what we saw last week.
Higher government bond yields can eventually make borrowing more expensive throughout the economy, affecting everything from mortgages to business loans.
They can also create more competition for stocks.
If investors can earn a more attractive return from lower risk investments, they're sometimes less willing to pay higher prices for stocks.
Technology companies can be particularly sensitive to that, which helps explain some of the weakness we saw in the Nasdaq last week.
Oil Brings Inflation Back Into the Conversation
Oil was another big part of the story.
Higher oil prices are a bit of a mixed bag from a Canadian perspective.
Canada is a major energy producer, so higher oil prices can be good for Canadian energy companies and parts of our economy.
But there is another side to that story.
More expensive oil can mean more expensive gasoline and transportation, and those costs can eventually make their way into the prices of other things we buy.
That's important because central banks have spent the past few years trying to get inflation under control.
If higher energy prices start pushing inflation higher again, it can make decisions around interest rates more difficult.
It's another reminder that inflation doesn't always move in a nice straight line.
What About Canada?
Here at home, the TSX held up better than the major U.S. indexes, finishing the week down approximately 0.3%.
Part of that comes back to how different our stock market is.
The Canadian market has much more exposure to energy, financials, mining and materials, while the U.S. market has a much larger concentration in technology.
That means the same economic news can affect the two markets very differently.
Canada also had inflation back in focus.
July inflation came in at 3.0%, up from 2.8% in June
At first glance, that doesn't sound particularly encouraging.
But it's worth looking underneath the headline.
A meaningful part of that increase came from higher gasoline prices. If energy prices remain elevated, that's something the Bank of Canada will have to consider as it thinks about where interest rates go from here.
For Canadian families, that's important because interest rates eventually work their way through mortgages, borrowing costs and savings rates.
But inflation wasn't the only Canadian story last week.
Trade with the United States quickly became an even bigger one.
Canada/U.S. Trade Talks: What Does This Actually Mean?
The Canada/U.S. trade situation took another turn over the weekend.
And I should probably put a time stamp on this section because, when it comes to tariffs and President Trump, things can change pretty quickly.
As of Sunday afternoon, negotiations between Canada and the United States had broken down and the U.S. was moving ahead with a 50% tariff on approximately $28 billion of Canadian exports.
Canada has said it plans to respond with matching tariffs beginning September 8.
So what does all of this actually mean?
A tariff is essentially a tax placed on goods coming into a country.
If a Canadian company sells a product to a customer in the United States and that product is subject to a 50% tariff, it suddenly becomes much more expensive for the American customer to buy.
That can hurt Canadian businesses because their products become less competitive. A company may have to lower its prices, accept smaller profits or potentially lose some of its U.S. customers.
And because Canada and the United States do so much business together, the effects can eventually make their way into jobs, economic growth and prices for consumers on both sides of the border.
That's why this matters.
How Big of a Deal Is This for Canada?
It's certainly not something we want to ignore, but I also think it's important to keep it in perspective.
Canada exports a huge variety of products to the United States, but these new tariffs don't apply equally to everything we sell.
Some very important Canadian exports, including energy and critical minerals, have so far avoided being targeted in the same way.
The current estimate is that these tariffs, if they remain in place, could reduce Canadian economic growth by roughly 0.5%.
That's meaningful, but it's very different from the much broader trade war that was being discussed in early 2025.
At that time, the Bank of Canada estimated that across the board 25% tariffs could reduce Canadian economic growth by approximately 2.4% in the first year.
So while the headlines sound pretty dramatic, we're not currently looking at that same scenario.
The bigger concern would be if things continue escalating.
Canada places tariffs on U.S. products, the U.S. responds with additional tariffs, Canada responds again and suddenly we're dealing with a much larger trade dispute.
Hopefully we don't get there.
Where Do Things Go From Here?
This probably isn't the end of the conversation.
Canada's retaliatory tariffs aren't scheduled to begin until September 8, which gives both countries some time to come back to the negotiating table.
It also gives American companies and states that do a lot of business with Canada time to make their concerns heard in Washington.
We've been through versions of this before.
Trade negotiations can involve a lot of very public back and forth before an agreement eventually gets reached.
That doesn't mean we should assume everything will work itself out perfectly.
But it also means we shouldn't assume today's headline is necessarily where this story ends.
What Does This Mean for Investors?
In the short term, probably more uncertainty.
Canadian companies that rely heavily on selling products into the United States could see some pressure, particularly if the dispute continues.
Other parts of the Canadian market may be much less affected.
And that's another good reminder of why diversification matters.
We don't want your financial future depending on one company, one industry, one country or one political decision.
There will always be things happening in the world that we can't predict.
Our job isn't to predict every tariff announcement or political negotiation correctly.
It's to build a financial plan and investment strategy that doesn't require us to.
What the Week Really Meant
If I had to summarize last week, I'd say investors were reminded that inflation, interest rates and politics can all become connected pretty quickly.
Higher oil prices brought inflation concerns back into focus.
Those concerns contributed to higher bond yields.
Higher yields put pressure on stocks, particularly technology companies.
And here in Canada, we now have another layer of uncertainty surrounding trade with our largest trading partner.
That's a lot for one week.
But it's also a pretty good example of why we don't build financial plans around predicting what happens next.
There will always be something making investors uncomfortable.
Over the past few years we've talked about inflation, interest rates, elections, tariffs, wars, recessions and technology valuations.
The headlines change. Uncertainty doesn't.
That's why we build financial plans around something much more personal and much more durable.
Your retirement date.
Your income needs.
Your family.
Your goals.
And the amount of risk you actually need to take to get there.
A difficult week in the markets shouldn't change those things.
Looking Ahead
There is quite a bit to watch this week.
In the U.S., investors will get another look at economic growth along with fresh inflation data.
The Personal Consumption Expenditures Index, or PCE, will be particularly important because it's one of the Federal Reserve's preferred measures of inflation.
With markets already paying close attention to oil prices and inflation, that report could get a little more attention than usual.
We'll also get consumer confidence, housing data and another reading on consumer sentiment.
And then there is Nvidia.
Nvidia reports earnings Wednesday and, given its size and the enormous amount of attention surrounding artificial intelligence, its results can have an impact well beyond one company's share price.
Here in Canada, I'll be watching the Canada/U.S. trade situation particularly closely.
The September 8 deadline gives both sides some time to find a path forward, and I wouldn't be surprised if we see plenty of headlines between now and then.
As always, we'll keep watching what happens without letting every headline dictate the investment plan.
Because there will always be another headline.
Our job is to make sure your financial plan is built to handle them.
This Week: Key Economic Data
Tuesday, August 25
- S&P Cotality Case-Shiller Home Price Index
- New Home Sales
- Consumer Confidence
Wednesday, August 26
- Durable Goods
- U.S. GDP, second estimate
- Personal Consumption Expenditures (PCE) Index
Thursday, August 27
- Weekly Jobless Claims
- Trade Balance in Goods
- Wholesale Inventories
- Retail Inventories
Friday, August 28
- University of Michigan Consumer Sentiment
This Week: Companies Reporting Earnings
Tuesday, August 25
- Intuit
Wednesday, August 26
- Nvidia
- CrowdStrike
- Salesforce
- Synopsys
Thursday, August 27
- Marvell Technology
- Autodesk
"“The most difficult thing is the decision to act, the rest is merely tenacity.”
– Amelia Earhart
Its body of stone shields a fiery heart. Under sufficient pressure, its head will depart. What is it?
Last Week's Riddle: I never complain no matter where I am led; I go around in circles, yet move straight ahead. What am I?
Answer: A wheel
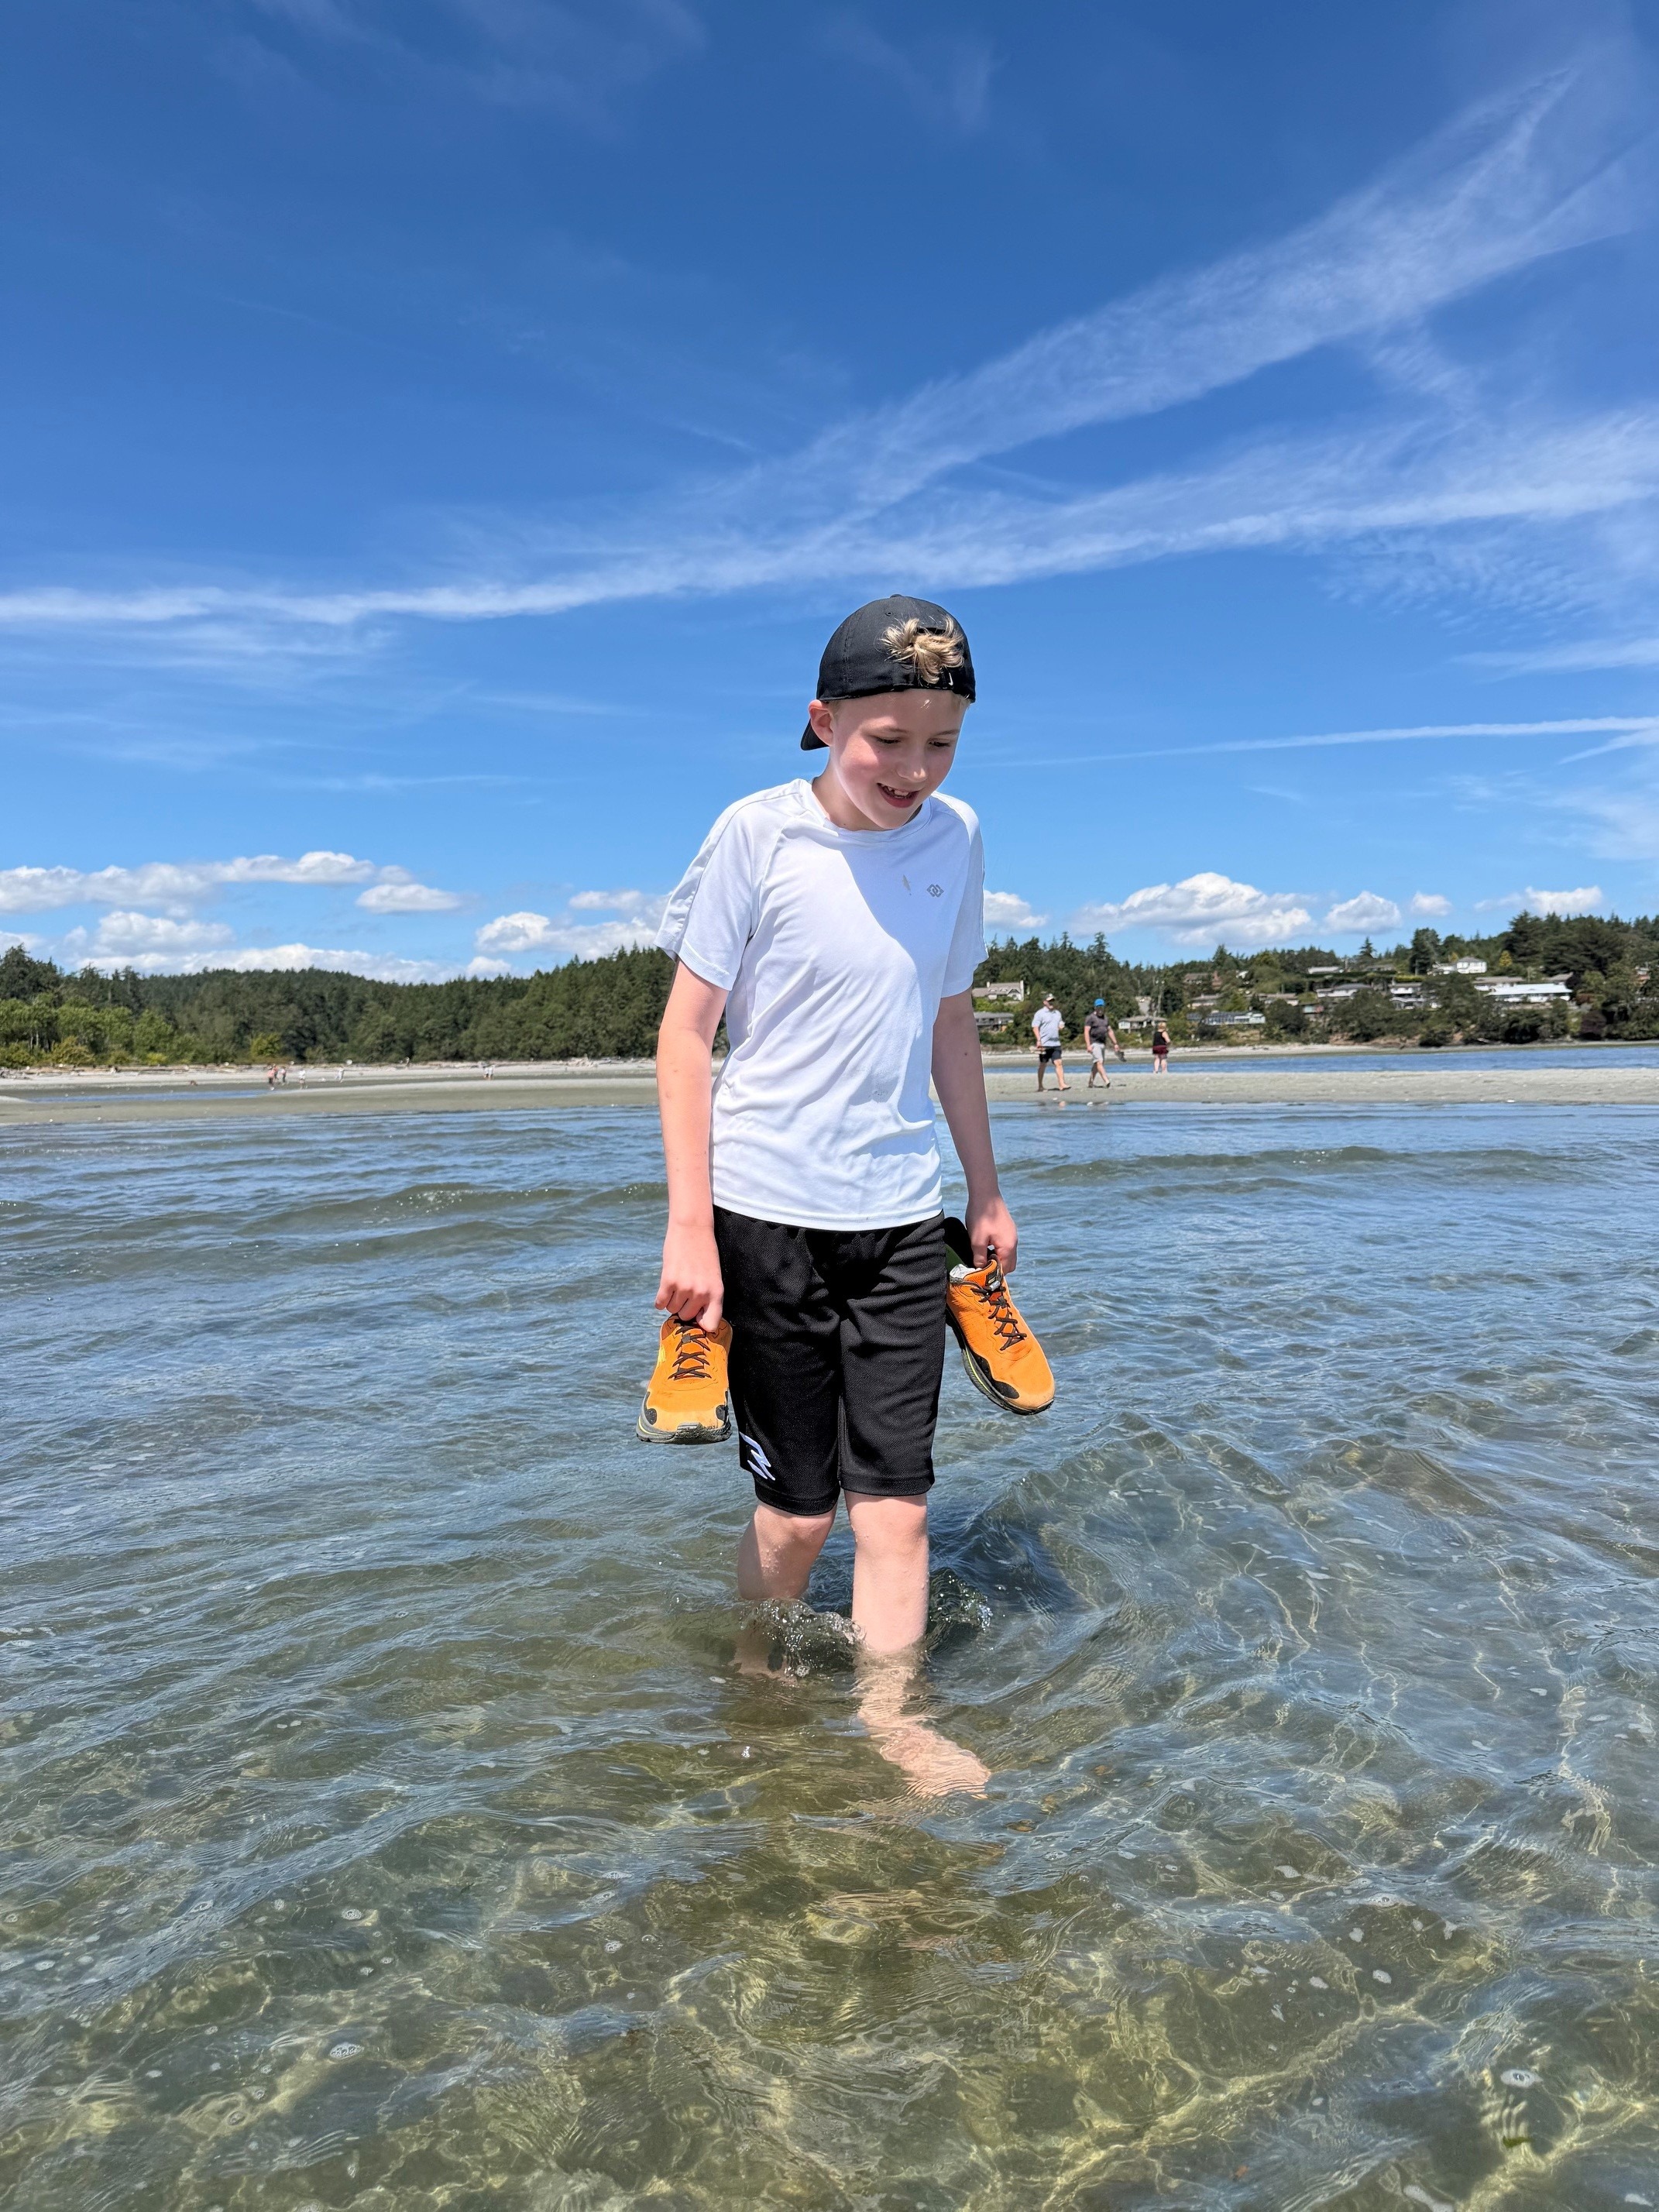
Joanne’s son, Matthew, hanging out at Witty’s Lagoon!
Footnotes And Sources
1. WSJ.com, August 21, 2026
2. Investing.com, August 21, 2026
3. WSJ.com, August 17, 2026
4. CNBC.com, August 18, 2026
5. CNBC.com, August 19, 2026
6. CNBC.com, August 20, 2026
7. WSJ.com, August 21, 2026
8. CNBC.com, August 19, 2026
9. creatoreconomy.so, June 25, 2025.
10. Very Well Fit, November 18, 2025
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost.
The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice.
The market indexes discussed are unmanaged, and generally, considered representative of their respective markets. Index performance is not indicative of the past performance of a particular investment. Indexes do not incur management fees, costs, and expenses. Individuals cannot directly invest in unmanaged indexes. Past performance does not guarantee future results.
The Dow Jones Industrial Average is an unmanaged index that is generally considered representative of large-capitalization companies on the U.S. stock market. The Nasdaq Composite is an index of the common stocks and similar securities listed on the Nasdaq stock market and considered a broad indicator of the performance of stocks of technology and growth companies. The MSCI EAFE Index was created by Morgan Stanley Capital International (MSCI) and serves as a benchmark of the performance of major international equity markets, as represented by 21 major MSCI indexes from Europe, Australia, and Southeast Asia. The S&P 500 Composite Index is an unmanaged group of securities that are considered to be representative of the stock market in general.
U.S. Treasury Notes are guaranteed by the federal government as to the timely payment of principal and interest. However, if you sell a Treasury Note prior to maturity, it may be worth more or less than the original price paid. Fixed income investments are subject to various risks including changes in interest rates, credit quality, inflation risk, market valuations, prepayments, corporate events, tax ramifications and other factors.
International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.
Please consult your financial professional for additional information.