


Markets Rebound as AI Optimism Returns, While Canada Shows Signs of Growth
Week Ending August 28, 2026
Markets had a better week last week, helped by falling bond yields and another round of strong earnings from some of the biggest technology companies.
Artificial intelligence was once again a major part of the story.
Several large technology companies reported that AI continues to contribute to their growth, which helped bring investors back into technology and semiconductor stocks after some weakness earlier in the week.
At the same time, inflation hasn't disappeared from the conversation.
New U.S. inflation numbers showed that prices are still running a little warmer than the Federal Reserve would like, and comments from Federal Reserve Chair Kevin Warsh reminded investors that interest rates may need to stay higher for longer.
So, once again, markets found themselves balancing two different stories.
Companies are generally doing well and economic growth has remained resilient.
But inflation is still hanging around.
Market Overview
Weekly Market Performance
- S&P 500: +0.49%
- Nasdaq Composite: +0.85%
- Dow Jones Industrial Average: +0.53%
- MSCI EAFE Index: -0.17%
- S&P/TSX Composite Index: approximately -0.18%
The Nasdaq led the major U.S. indexes, gaining just under 1% as technology and semiconductor stocks bounced back. The S&P 500 and Dow also finished the week higher.
Here at home, the TSX was essentially flat for the week, declining approximately 0.18%. The index finished Friday at 36,553.92 after briefly moving above 37,000 during Wednesday's trading.
AI Is Still Driving a Lot of the Market Conversation
We've spent quite a bit of time talking about artificial intelligence over the past couple of years, and last week was another reminder of just how influential it has become.
Technology stocks started the week on a weaker note, but that changed as companies began reporting earnings.
Several large technology companies reported strong results and continued demand related to AI.
Nvidia was one of the standouts, reporting another significant increase in both revenue and earnings. Other technology companies also reported encouraging results, which helped lift the broader technology sector.
Why does this matter beyond just a handful of technology companies?
Some of these companies have become so large that their movements can have a noticeable impact on the overall market.
When investors feel optimistic about AI spending and future growth, it can lift the entire technology sector.
Of course, the opposite can also be true.
That's why I think it's important to remember that while AI is an exciting long-term theme, it doesn't mean every AI-related company will go up indefinitely or that there won't be periods of volatility along the way.
Inflation Isn't Quite Finished With Us Yet
The other big story last week was inflation.
The Personal Consumption Expenditures Index, better known as PCE, is one of the Federal Reserve's preferred ways of measuring inflation.
The latest numbers came in slightly higher than expected overall, although core inflation, which removes the more volatile food and energy categories, was roughly in line with expectations.
That may sound like a lot of economic jargon, but the important part is pretty simple.
Inflation is proving somewhat stubborn.
We've made a lot of progress from the inflation levels we saw a few years ago, but getting inflation the rest of the way back down isn't necessarily going to happen quickly or smoothly.
And that matters for interest rates.
What Did We Learn From Jackson Hole?
Central bankers from around the world gathered in Jackson Hole, Wyoming last week for the Federal Reserve's annual economic conference.
These meetings tend to get a lot of attention because investors are looking for clues about where interest rates might be headed next.
Fed Chair Kevin Warsh made it clear that inflation remains a concern.
Several other Federal Reserve officials also suggested that they aren't in a hurry to lower interest rates, and some appeared open to rates remaining higher if that's what's needed to keep inflation under control.
Markets generally took the message to mean that the Federal Reserve is still going to be cautious.
That's important because investors have spent much of the past few years trying to guess when rates will fall.
The reality is that central banks don't have a predetermined schedule.
They react to the economic information in front of them.
If inflation stays stubborn, rates may remain higher.
If inflation continues cooling and the economy slows, they have more flexibility.
What About Canada?
We had some encouraging economic news here at home last week.
Statistics Canada reported that the Canadian economy grew 0.8% in the second quarter of 2026.
Growth was helped by higher exports, household spending and increased investment by businesses. Even more encouragingly, Canada's real GDP per person increased 1.0% during the quarter.
That's a welcome improvement after a relatively flat start to the year.
It doesn't mean the Canadian economy is suddenly booming.
There are still challenges, particularly around trade, borrowing costs and affordability.
But it does show that the economy has been more resilient than some of the headlines might suggest.
Canada/U.S. Trade Is Still a Big Story
Of course, we can't talk about the Canadian economy right now without talking about trade.
The new 50% U.S. tariffs on approximately $27.6 billion of Canadian goods came into effect on August 22.
Canada responded last week by confirming that it intends to match those tariffs dollar for dollar and rate for rate on U.S. goods.
This is something we're going to continue watching closely.
The encouraging part is that the tariffs still affect a relatively small portion of Canada's overall exports to the United States rather than everything Canada sells south of the border.
That doesn't make them insignificant, particularly for the Canadian businesses and industries directly affected.
But it is important context when we're reading some of the more dramatic headlines.
The bigger risk would be if the dispute continues escalating and tariffs spread to a much larger portion of trade between the two countries.
For now, that's not where we are.
What Does This Mean for Investors?
If last week showed us anything, it's how quickly the market's attention can move.
One day we're talking about tariffs.
The next day it's inflation.
Then it's interest rates.
And then Nvidia reports earnings and suddenly everyone is talking about artificial intelligence again.
That's normal.
There will always be a new piece of information for markets to digest.
The mistake is thinking that we need to change our long-term investment strategy every time the headline changes.
We don't.
Our portfolios aren't built around knowing exactly what the Federal Reserve will do next, which AI company will have the best quarter or when Canada and the United States will reach their next trade agreement.
They're built around diversification, appropriate risk and, most importantly, your financial plan.
What the Week Really Meant
If I had to summarize last week, I'd say the underlying message was actually fairly encouraging.
Corporate earnings continue to show strength in important parts of the market.
The Canadian economy grew more than it did earlier in the year.
And despite all of the uncertainty surrounding inflation, interest rates and trade, markets continue to work through the headlines.
That doesn't mean everything is perfect.
Inflation is still a concern.
Interest rates may stay higher than some investors had hoped.
And the Canada/U.S. trade situation remains uncertain.
But uncertainty isn't unusual.
There will always be something happening that we can't predict.
That's why our financial plans aren't built around predicting what happens next.
They're built around your retirement.
Your income needs.
Your family.
Your goals.
And making sure your investments are taking the right amount of risk to get you where you want to go.
Looking Ahead
This week, the biggest economic story will probably be employment.
We'll get several reports on the U.S. labour market throughout the week, culminating with the monthly U.S. employment report on Friday.
That's important because the Federal Reserve is watching both inflation and employment when making decisions about interest rates.
A strong job market gives the Fed more room to keep rates higher if inflation remains stubborn.
A noticeably weaker job market could change that conversation.
Here in Canada, interest rates will also be in focus with the Bank of Canada decision coming up.
With Canadian economic growth improving but trade uncertainty remaining elevated, there is a lot for the Bank of Canada to consider. Current expectations are that the Bank will leave its policy rate unchanged at 2.25%.
As always, we'll keep watching the economic numbers and the headlines.
But we'll also keep them in perspective.
Because the goal isn't to react to every piece of news.
It's to have a financial plan that can handle the fact that there will always be another one.
This Week: Key Economic Data
Tuesday, September 1
- U.S. Manufacturing PMI
- Construction Spending
- Job Openings
Wednesday, September 2
- ADP Private Sector Employment Report
- Factory Orders
- Federal Reserve Beige Book
Thursday, September 3
- U.S. Trade Balance
- Weekly Jobless Claims
- Services PMI
Friday, September 4
- U.S. Employment Report
- This Week: Companies Reporting Earnings
Tuesday, September 1
- Dell Technologies
- Palo Alto Networks
- Medtronic
Wednesday, September 2
- Broadcom
- Snowflake
- Hewlett Packard Enterprise
Thursday, September 3
- Ciena
"It's hard to be a diamond in a rhinestone world."
– Dolly Parton
A man bet his neighbor that his dog could jump higher than his neighbor's hedge. The neighbor accepted the bet and lost. Why?
Last Week's Riddle: Its body of stone shields a fiery heart. Under sufficient pressure, its head will depart. What is it?
Answer: A volcano
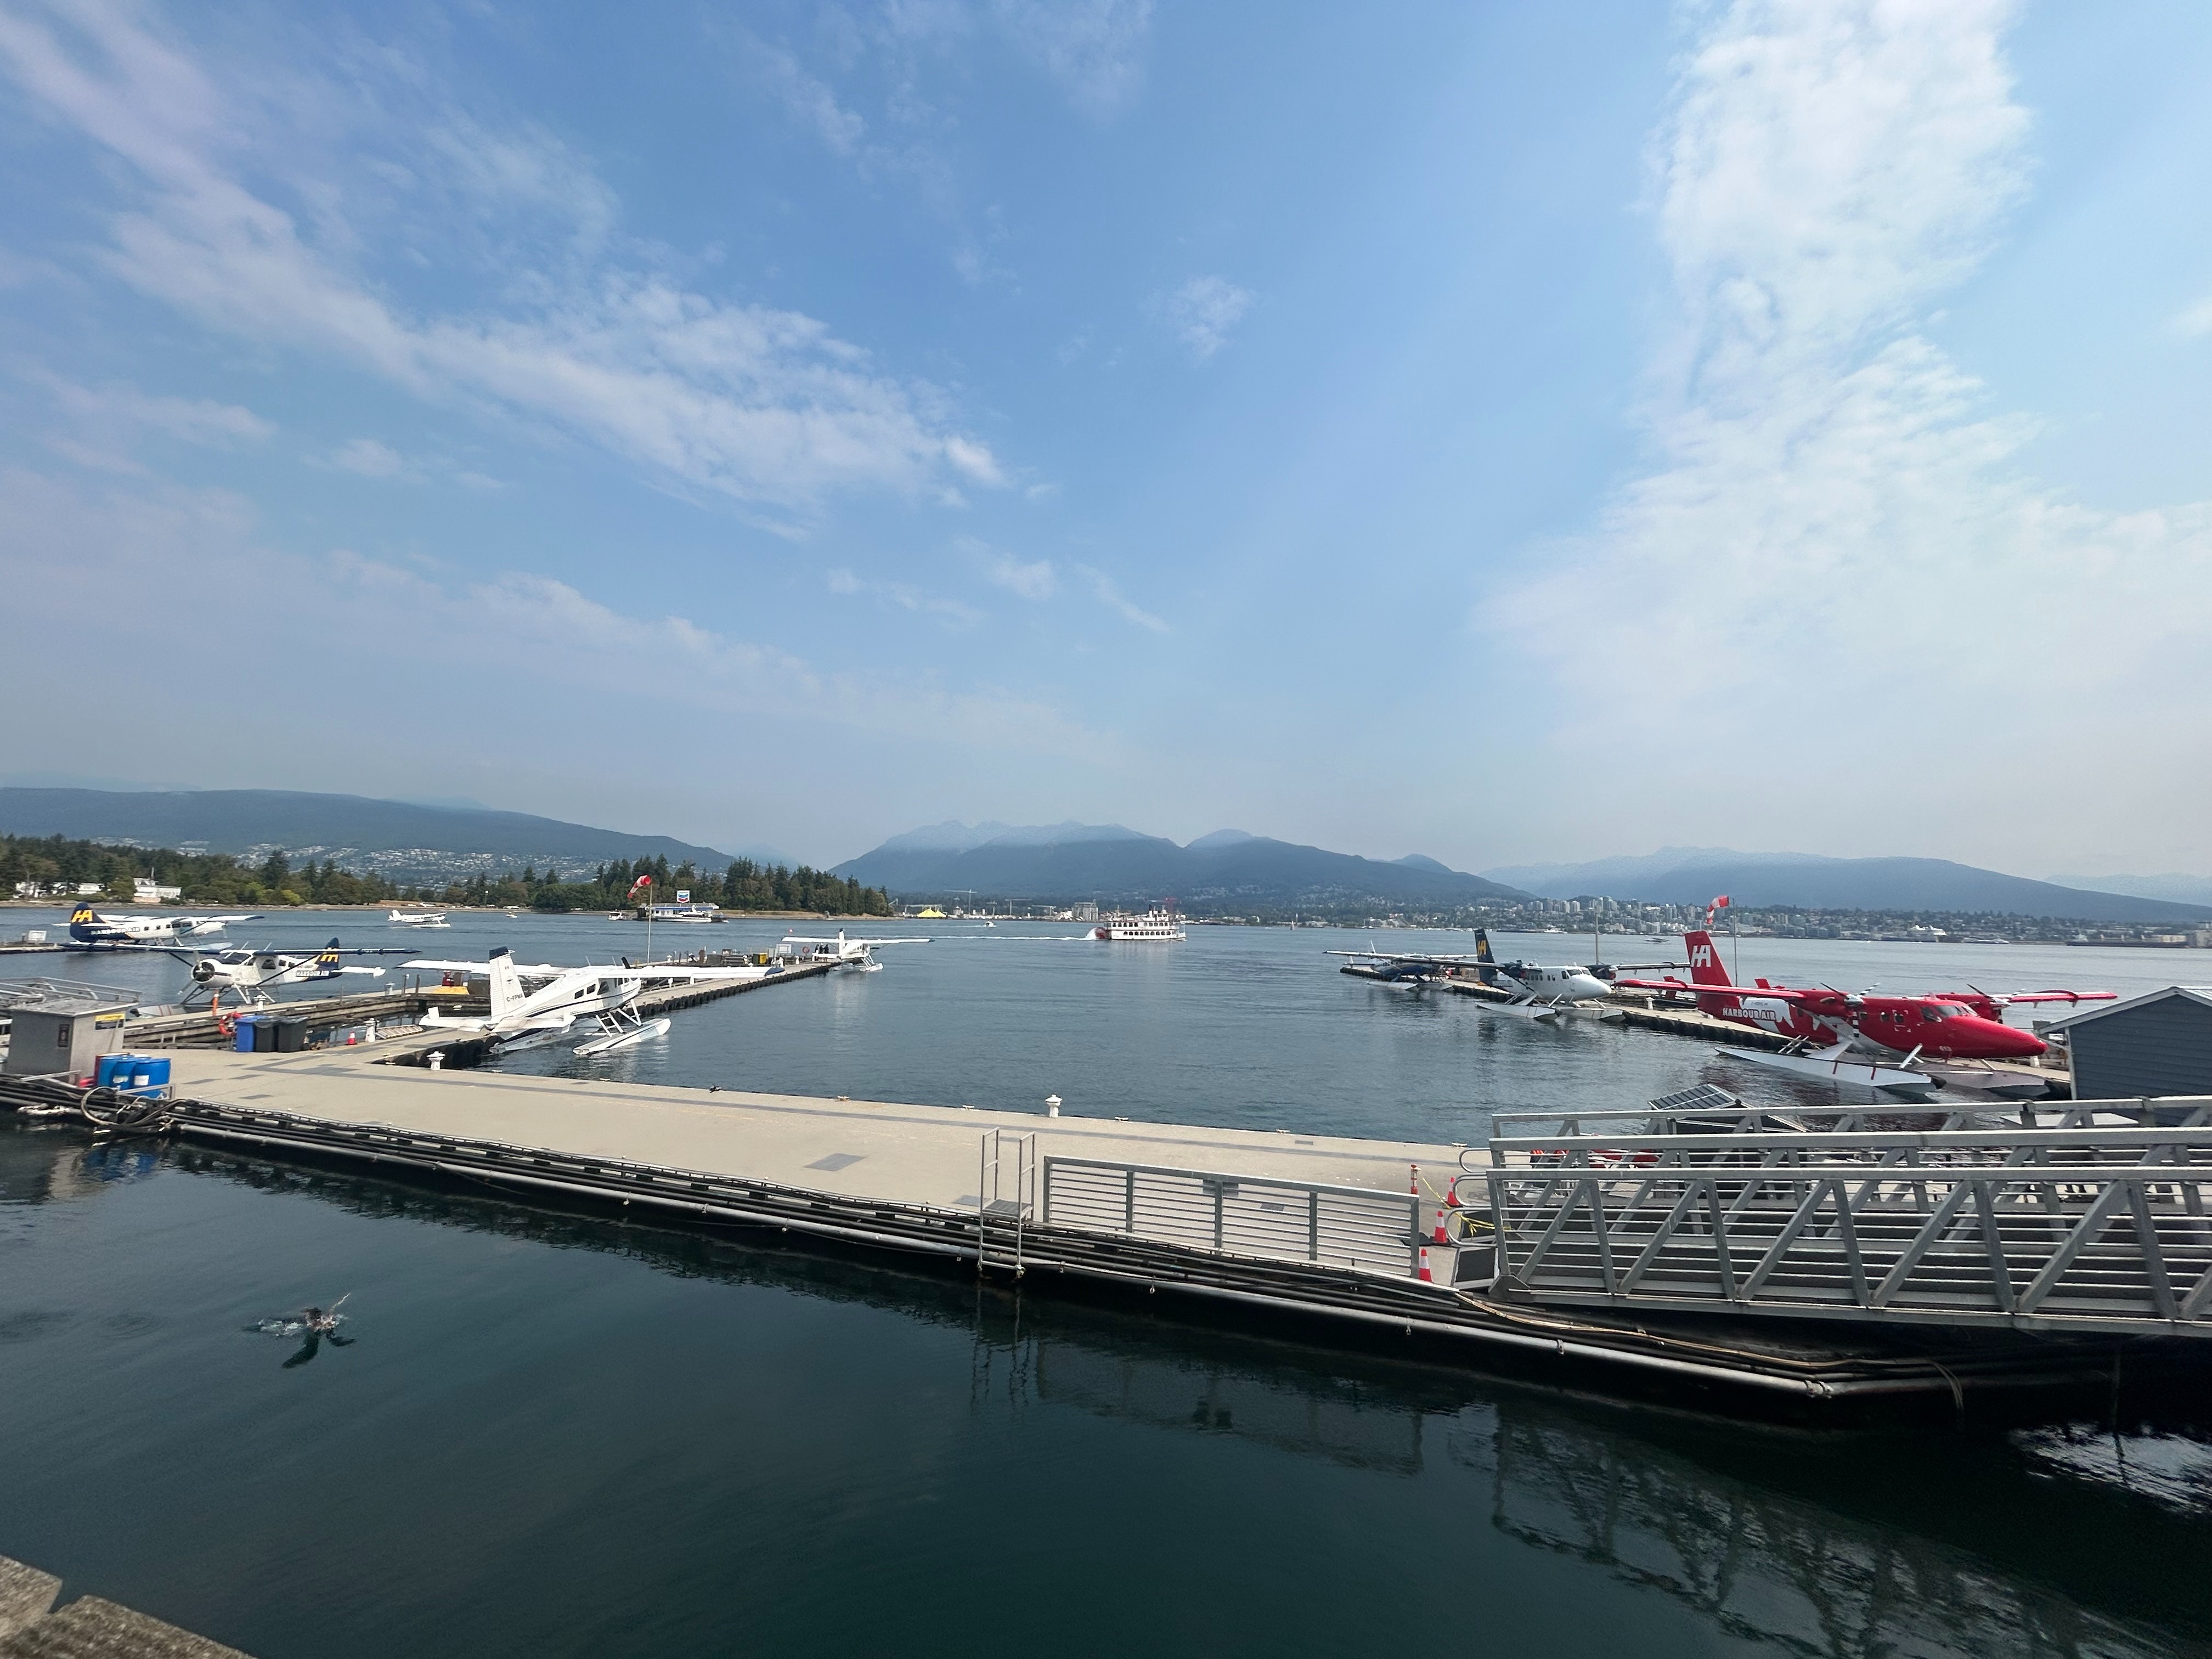
A beautiful Vancouver view from Tanya's recent trip.
Footnotes And Sources
1. WSJ.com, August 28, 2026
2. Investing.com, August 28, 2026
3. CNBC.com, August 24, 2026
4. CNBC.com, August 25, 2026
5. CNBC.com, August 26, 2026
6. CNBC.com, August 27, 2026
7. WSJ.com, August 28, 2026
8. WSJ.com, August 28, 2026
9. BuzzFeed, October 15, 2025.
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost.
The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice.
The market indexes discussed are unmanaged, and generally, considered representative of their respective markets. Index performance is not indicative of the past performance of a particular investment. Indexes do not incur management fees, costs, and expenses. Individuals cannot directly invest in unmanaged indexes. Past performance does not guarantee future results.
The Dow Jones Industrial Average is an unmanaged index that is generally considered representative of large-capitalization companies on the U.S. stock market. The Nasdaq Composite is an index of the common stocks and similar securities listed on the Nasdaq stock market and considered a broad indicator of the performance of stocks of technology and growth companies. The MSCI EAFE Index was created by Morgan Stanley Capital International (MSCI) and serves as a benchmark of the performance of major international equity markets, as represented by 21 major MSCI indexes from Europe, Australia, and Southeast Asia. The S&P 500 Composite Index is an unmanaged group of securities that are considered to be representative of the stock market in general.
U.S. Treasury Notes are guaranteed by the federal government as to the timely payment of principal and interest. However, if you sell a Treasury Note prior to maturity, it may be worth more or less than the original price paid. Fixed income investments are subject to various risks including changes in interest rates, credit quality, inflation risk, market valuations, prepayments, corporate events, tax ramifications and other factors.
International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.
Please consult your financial professional for additional information.