


Inflation, Oil and Interest Rates Put Markets Back on Edge
Week Ending September 11, 2026
After taking last week off for the long weekend, we're back with our weekly market update.
And there was quite a bit to catch up on.
Markets had a more difficult week last week as investors focused on rising oil prices, higher bond yields and, once again, inflation.
Stocks came under pressure through the middle of the week as oil prices continued to climb.
At the same time, the yield on the 10 year U.S. Treasury reached its highest level in roughly three years, which added another layer of concern for investors.
Then came two important inflation reports.
By Friday, markets managed to recover some of their losses as oil prices pulled back and investors digested the latest inflation numbers.
So, once again, markets found themselves balancing a few different stories.
Inflation is still proving stubborn.
Oil prices have been moving higher.
And investors are trying to figure out what all of this means for interest rates.
Market Overview
Weekly Market Performance
- S&P 500: -0.8%
- Nasdaq Composite: -0.7%
- Dow Jones Industrial Average: -1.6%
- MSCI EAFE Index: approximately -1.3%
- S&P/TSX Composite Index: approximately -2.2%
It was a tougher week across most major markets.
The Dow saw the largest decline among the major U.S. indexes, while the S&P 500 and Nasdaq also finished lower.
Here at home, the TSX fell approximately 2.2% for the week, marking its fourth consecutive weekly decline.
Despite a better day on Friday, it wasn't enough to erase the losses from earlier in the week.
Inflation Is Back in the Spotlight
Inflation was one of the biggest stories last week.
On Thursday, we received the latest Producer Price Index, or PPI.
This measures the prices businesses receive for the goods and services they produce and can sometimes give us an early indication of where consumer prices may eventually be headed.
Producer prices increased 0.4% in August compared with the previous month, which was roughly in line with expectations.
Then on Friday, we received the number investors were really waiting for.
The Consumer Price Index showed that U.S. inflation held steady at 3.4% year over year in August.
Markets actually responded relatively well to the report, with stocks rebounding on Friday.
Why Does Inflation Still Matter So Much?
We've been talking about inflation for years now, so it would be understandable if everyone was getting a little tired of hearing about it.
But it still matters.
The Federal Reserve would like to see inflation sustainably moving back toward its 2% target.
At 3.4%, we're not there yet.
And the last part of the journey can sometimes be the hardest.
Inflation has come down considerably from where it was a few years ago, but that doesn't necessarily mean it will continue falling in a straight line.
That matters because interest rates are one of the main tools central banks use to control inflation.
If inflation remains stubborn, rates may need to stay higher.
If inflation starts moving convincingly lower, the Federal Reserve has more flexibility.
That's why investors pay so much attention to every new inflation report.
Oil Is Complicating the Inflation Story
Oil was another major part of the market story last week.
Prices moved sharply higher during the week, briefly adding to concerns that inflation could become more difficult to bring under control.
Oil affects much more than what we pay at the gas station.
Higher energy prices can increase transportation, manufacturing and shipping costs, which can eventually work their way through many different parts of the economy.
For Canada, however, the story is a little more complicated.
We're a major energy producer.
That means higher oil prices can benefit Canadian energy companies and parts of our economy, while at the same time increasing costs for Canadian households and businesses.
It's another example of why economic news isn't always simply good or bad.
There are usually two sides to the story.
What About Canada?
There is plenty happening here at home as well.
The TSX had a difficult week, falling approximately 2.2%.
Canada's economy is also navigating many of the same issues we're seeing south of the border, including inflation, higher energy prices, trade uncertainty and the impact of interest rates.
The Bank of Canada left its policy rate unchanged at 2.25% earlier this month.
Now attention turns back to inflation.
Statistics Canada will release Canada's August Consumer Price Index this week.
Canada's annual inflation rate was 3.0% in July, up from 2.8% in June.
The new report will give us a better idea of whether inflationary pressures are continuing to build or beginning to settle down.
Given what has been happening with energy prices, it will be an important number to watch.
What Does This Mean for Investors?
Last week was another good example of how quickly the market narrative can change.
One week investors are focused on corporate earnings and artificial intelligence.
The next week everyone is talking about oil, inflation and bond yields.
And this week, attention will shift again to central banks and interest rates.
That's normal.
Markets are constantly processing new information.
The important thing is not to confuse short term market reactions with changes to your long term financial plan.
A difficult week in the markets doesn't necessarily mean something has fundamentally changed.
Just as a strong week doesn't mean all of the risks have disappeared.
Our portfolios are designed knowing that there will be periods of volatility along the way.
What the Week Really Meant
If I had to summarize last week, I would say it was really about one question.
Is inflation going to be harder to bring down than investors hoped?
Right now, we don't have a definitive answer.
Inflation is still above central bank targets.
Oil prices have added another potential source of pressure.
And bond markets are reminding investors that interest rates may not fall as quickly as some had expected.
But none of that means we should be making dramatic changes based on a single week of market activity.
Economic conditions change.
Markets adjust.
And new information is constantly being priced in.
That's why our financial plans aren't built around predicting the next inflation report or interest rate decision.
They're built around your retirement.
Your income needs.
Your family.
Your goals.
And making sure your investments are taking the right amount of risk to get you where you want to go.
Looking Ahead
This week, central banks and inflation will be front and centre.
Here in Canada, we'll receive the latest Consumer Price Index, giving us a fresh look at inflation and how prices are changing for Canadian households.
In the United States, the Federal Reserve begins its two day meeting on Tuesday, with its latest interest rate decision coming Wednesday.
Investors will be paying close attention not only to the decision itself, but also to what Federal Reserve Chair Kevin Warsh says about inflation and the path for interest rates from here.
We'll also get new information on retail sales, housing, jobless claims and industrial production.
As always, there will be plenty of headlines.
But we'll keep them in perspective.
Because the goal isn't to predict every move in oil prices, interest rates or the stock market.
It's to have a financial plan that can handle the fact that all three will change over time.
This Week: Key Economic Data
Monday, September 14
- Canada Consumer Price Index (CPI)
- Canadian Housing Starts
Tuesday, September 15
- Federal Open Market Committee (FOMC) Meeting, Day 1
- U.S. Retail Sales
- Import Prices
- Manufacturing and Trade Inventories
- NAHB Housing Market Index
Wednesday, September 16
- Federal Open Market Committee (FOMC) Meeting, Day 2
- Federal Reserve Interest Rate Decision
Thursday, September 17
- U.S. Housing Starts
- Weekly Jobless Claims
- Pending Home Sales
Friday, September 18
- Industrial Production
- Capacity Utilization
- Leading Economic Indicators
This Week: Companies Reporting Earnings
There are no major companies reporting earnings this week.
"Fight for the things that you care about, but do it in a way that will lead others to join you.”
– Ruth Bader Ginsburg
A 400-yard long promenade has an ornate brass bench every 100 yards on both sides, including ones at its beginning and end. So in total, how many benches are there along this promenade?
Last Week's Riddle: A man bet his neighbor that his dog could jump higher than his neighbor's hedge. The neighbor accepted the bet and lost. Why?
Answer: Because the hedge can`t jump
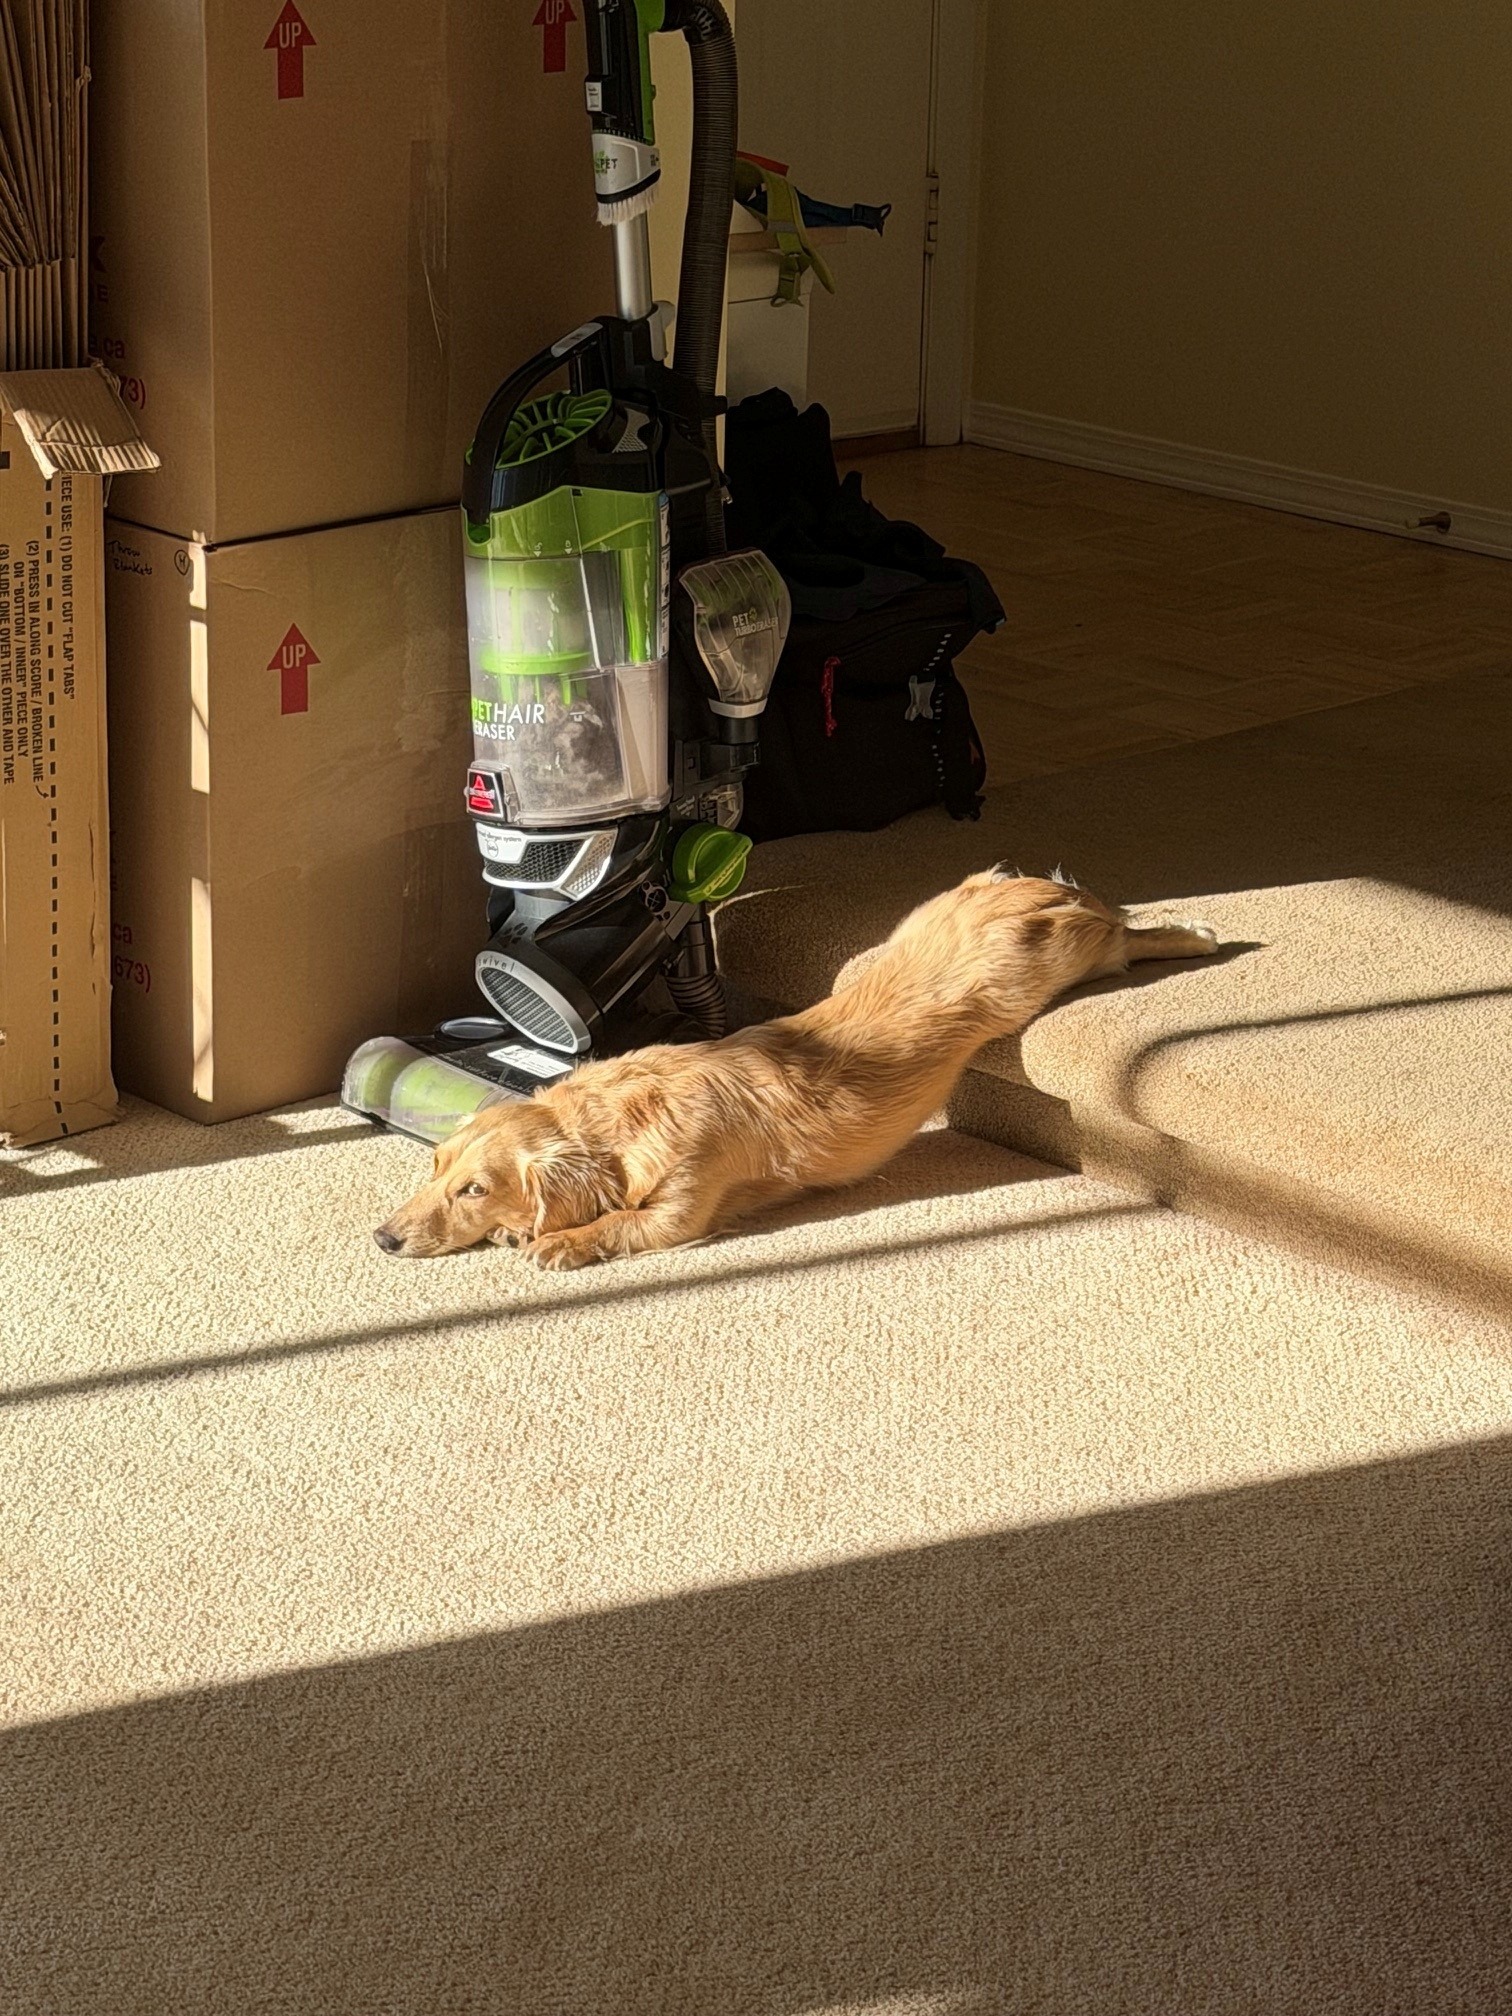
Austin goes to great lengths to capture the most sunshine!
Footnotes And Sources
1. WSJ.com, September 11, 2026
2. Investing.com, September 11, 2026
3. CNBC.com, September 8, 2026
4. CNBC.com, September 9, 2026
5. CNBC.com, September 9, 2026
6. WSJ.com, September 11, 2026
7. CNBC.com, September 10, 2026
8. WSJ.com, September 11, 2026
9. Theeverymom.com, July 21, 2026.
10. Mensjournal.com, November 18, 2025
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost.
The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice.
The market indexes discussed are unmanaged, and generally, considered representative of their respective markets. Index performance is not indicative of the past performance of a particular investment. Indexes do not incur management fees, costs, and expenses. Individuals cannot directly invest in unmanaged indexes. Past performance does not guarantee future results.
The Dow Jones Industrial Average is an unmanaged index that is generally considered representative of large-capitalization companies on the U.S. stock market. The Nasdaq Composite is an index of the common stocks and similar securities listed on the Nasdaq stock market and considered a broad indicator of the performance of stocks of technology and growth companies. The MSCI EAFE Index was created by Morgan Stanley Capital International (MSCI) and serves as a benchmark of the performance of major international equity markets, as represented by 21 major MSCI indexes from Europe, Australia, and Southeast Asia. The S&P 500 Composite Index is an unmanaged group of securities that are considered to be representative of the stock market in general.
U.S. Treasury Notes are guaranteed by the federal government as to the timely payment of principal and interest. However, if you sell a Treasury Note prior to maturity, it may be worth more or less than the original price paid. Fixed income investments are subject to various risks including changes in interest rates, credit quality, inflation risk, market valuations, prepayments, corporate events, tax ramifications and other factors.
International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.
Please consult your financial professional for additional information.