


Interest Rates, Bond Yields and AI Keep Investors Guessing
Week Ending September 18, 2026
Markets finished last week mixed as investors worked through another busy week of interest rates, bond yields, oil prices and artificial intelligence.
The biggest event of the week was the U.S. Federal Reserve's latest interest rate decision.
As expected, the Fed raised interest rates by 0.25%.
But as is often the case, the decision itself wasn't really the biggest story.
Investors were more interested in what the Federal Reserve had to say about what comes next.
At the same time, the yield on the 10 year U.S. Treasury moved back toward 5%, putting some pressure on stocks.
Oil prices remained volatile.
And artificial intelligence continued to be one of the stronger areas of the market, helping the technology heavy Nasdaq finish the week higher.
So, once again, there wasn't one single story driving markets.
Interest rates are still high.
Inflation is still a concern.
Bond yields are putting pressure on borrowing costs.
And investors are trying to decide how much further central banks may need to go.
Market Overview
Weekly Market Performance
- S&P 500: -0.09%
- Nasdaq Composite: +0.72%
- Dow Jones Industrial Average: -1.70%
- MSCI EAFE Index: -1.32%
- S&P/TSX Composite Index: approximately +0.3%
It was a mixed week across the major markets.
The Nasdaq was the strongest of the major U.S. indexes, helped by strength in technology and AI related companies.
The Dow had a more difficult week, falling 1.7%, while the S&P 500 finished almost flat.
Here at home, the TSX managed to finish slightly higher for the week after four consecutive weeks of declines.
The Federal Reserve Raises Rates
The biggest event of the week came on Wednesday.
The Federal Reserve raised its key interest rate by 0.25%, bringing its target range to 3.75% to 4.00%.
The increase was widely expected.
What investors really wanted to know was whether the Fed believes more increases will be necessary.
And right now, the answer appears to be that they could be.
The Federal Reserve is still concerned about inflation and most Fed officials indicated that at least one more adjustment could be appropriate before the end of the year.
That doesn't mean another increase is guaranteed.
It means the Fed is keeping its options open
If inflation remains stubborn, it may need to do more.
If inflation starts moving lower, it has more flexibility.
Sound familiar?
We've been having some version of this conversation for quite a while now.
Why Are Bond Yields Such a Big Deal?
Bond yields were another important part of the story last week.
The yield on the 10 year U.S. Treasury moved back toward 5%, a level we haven't seen since 2023.
That matters for a few reasons.
Higher bond yields can make borrowing more expensive.
They can affect mortgage rates.
They can increase financing costs for businesses.
And they can also make bonds more attractive compared with stocks.
When investors can earn a higher return from relatively safer investments, they may be less willing to pay high prices for stocks.
That's one of the reasons markets can become more volatile when bond yields move sharply higher.
It doesn't necessarily mean something is wrong.
It simply changes the math investors are using when deciding what different investments are worth.
AI Isn't Going Away
Artificial intelligence continued to be another major market story.
We've talked quite a bit about AI this year, and I don't think that conversation is going away anytime soon.
Technology and semiconductor companies connected to AI helped support the Nasdaq last week.
But investors are also becoming more selective.
There is clearly a lot of excitement around the potential of artificial intelligence.
There is also a lot of money being spent to build the infrastructure needed to support it.
Eventually, investors will want to see that spending translate into profits.
So while AI continues to be a powerful market theme, we should expect some ups and downs along the way.
That's normal when expectations are high.
What About Canada?
There was important news here at home as well.
The S&P/TSX Composite Index finished the week up approximately 0.3%, breaking a four week stretch of weekly declines.
But the bigger Canadian story was inflation.
Statistics Canada reported that Canada's annual inflation rate was 3.0% in August, unchanged from July.
That was probably a little more encouraging than the headline number initially sounds.
Grocery prices increased 2.8% compared with a year ago, down from 3.1% in July.
In fact, grocery prices increased at a slower pace than overall inflation for the first time in more than two years.
Gasoline is still having a big impact on the numbers.
Gasoline prices were 22.8% higher than a year ago.
When gasoline is removed from the calculation, inflation was 2.4%.
That's an important distinction.
The Bank of Canada can't control the price of oil.
What it is watching for is whether higher energy prices start pushing up prices throughout the rest of the economy.
For now, Canada's inflation picture remains a little complicated.
Inflation is still above the Bank of Canada's 2% target.
But underneath the headline number, there are also signs that some price pressures are easing.
What Does This Mean for Investors?
Last week was another good example of why markets can sometimes feel confusing.
The Federal Reserve raised interest rates.
Bond yields moved higher.
Oil prices remained volatile.
The Dow fell.
The Nasdaq rose.
And the TSX managed to finish slightly higher.
There isn't always one simple explanation for what markets are doing.
And there doesn't need to be.
Markets are constantly balancing different pieces of information and trying to determine what they mean for the future.
For long term investors, the important thing is not to react to every move.
A quarter point change in interest rates doesn't suddenly change your retirement plan.
Neither does one week of rising bond yields.
And one strong or weak week for technology stocks doesn't change the reason we diversify portfolios.
Our plans are built knowing that markets will move around.
What the Week Really Meant
If I had to summarize last week, I would say it was really about one question.
How high do interest rates need to go before inflation is truly under control?
We still don't know the answer.
The Federal Reserve believes inflation remains too high.
Canada's inflation rate is still sitting at 3%.
Oil prices have complicated the picture.
And higher bond yields are reminding investors that borrowing costs may remain elevated for a while.
But there were also some encouraging signs.
Canadian grocery inflation slowed.
Technology stocks continued to show strength.
And despite everything happening during the week, the S&P 500 finished almost exactly where it started.
That's worth remembering.
There will always be something for investors to worry about.
Interest rates.
Inflation.
Oil.
Politics.
Artificial intelligence.
The list changes, but there is always a list.
That's why our financial plans aren't built around predicting what the Federal Reserve will do at its next meeting.
They're built around your retirement.
Your income needs.
Your family.
Your goals.
And making sure your investments are taking the right amount of risk to get you where you want to go.
Looking Ahead
After a busy week for central banks, attention now shifts back toward the economy.
Investors will be watching new information on manufacturing and services, jobless claims, housing, durable goods and consumer confidence.
Bond yields will also remain important.
If yields continue moving higher, that could create some additional pressure on stocks.
If they settle down, markets may get a little breathing room.
Oil prices will be another area to watch, particularly because of their potential impact on inflation.
And, of course, AI and technology aren't going anywhere.
As always, there will be plenty of headlines.
But we'll keep them in perspective.
Because the goal isn't to predict every move in interest rates, oil prices, bond yields or the stock market.
It's to have a financial plan that can handle the fact that all of them will change over time.
This Week: Key Economic Data
Tuesday, September 22
- Richmond Fed President Tom Barkin speaks
Wednesday, September 23
- U.S. Manufacturing Purchasing Managers Index
- U.S. Services Purchasing Managers Index
Thursday, September 24
- Weekly Jobless Claims
- New Home Sales
- Richmond Fed President Tom Barkin speaks
Friday, September 25
- Durable Goods Orders
- University of Michigan Consumer Sentiment
- This Week: Companies Reporting Earnings
This Week: Companies Reporting Earnings
Tuesday, September 22
- AutoZone
Wednesday, September 23
- Cintas
- Paychex
Thursday, September 24
- Costco Wholesale
"I like thinking big. I always have. To me it's very simple: if you're going to be thinking anyway, you might as well think big."
– Warren Buffett
They are captured by mud and snow, left behind but never taken, and rarely seen in isolation. What are they?
Last Week's Riddle: A 400-yard long promenade has an ornate brass bench every 100 yards on both sides, including ones at its beginning and end. So in total, how many benches are there along this promenade?
Answer: 10 benches, 5 on either side.
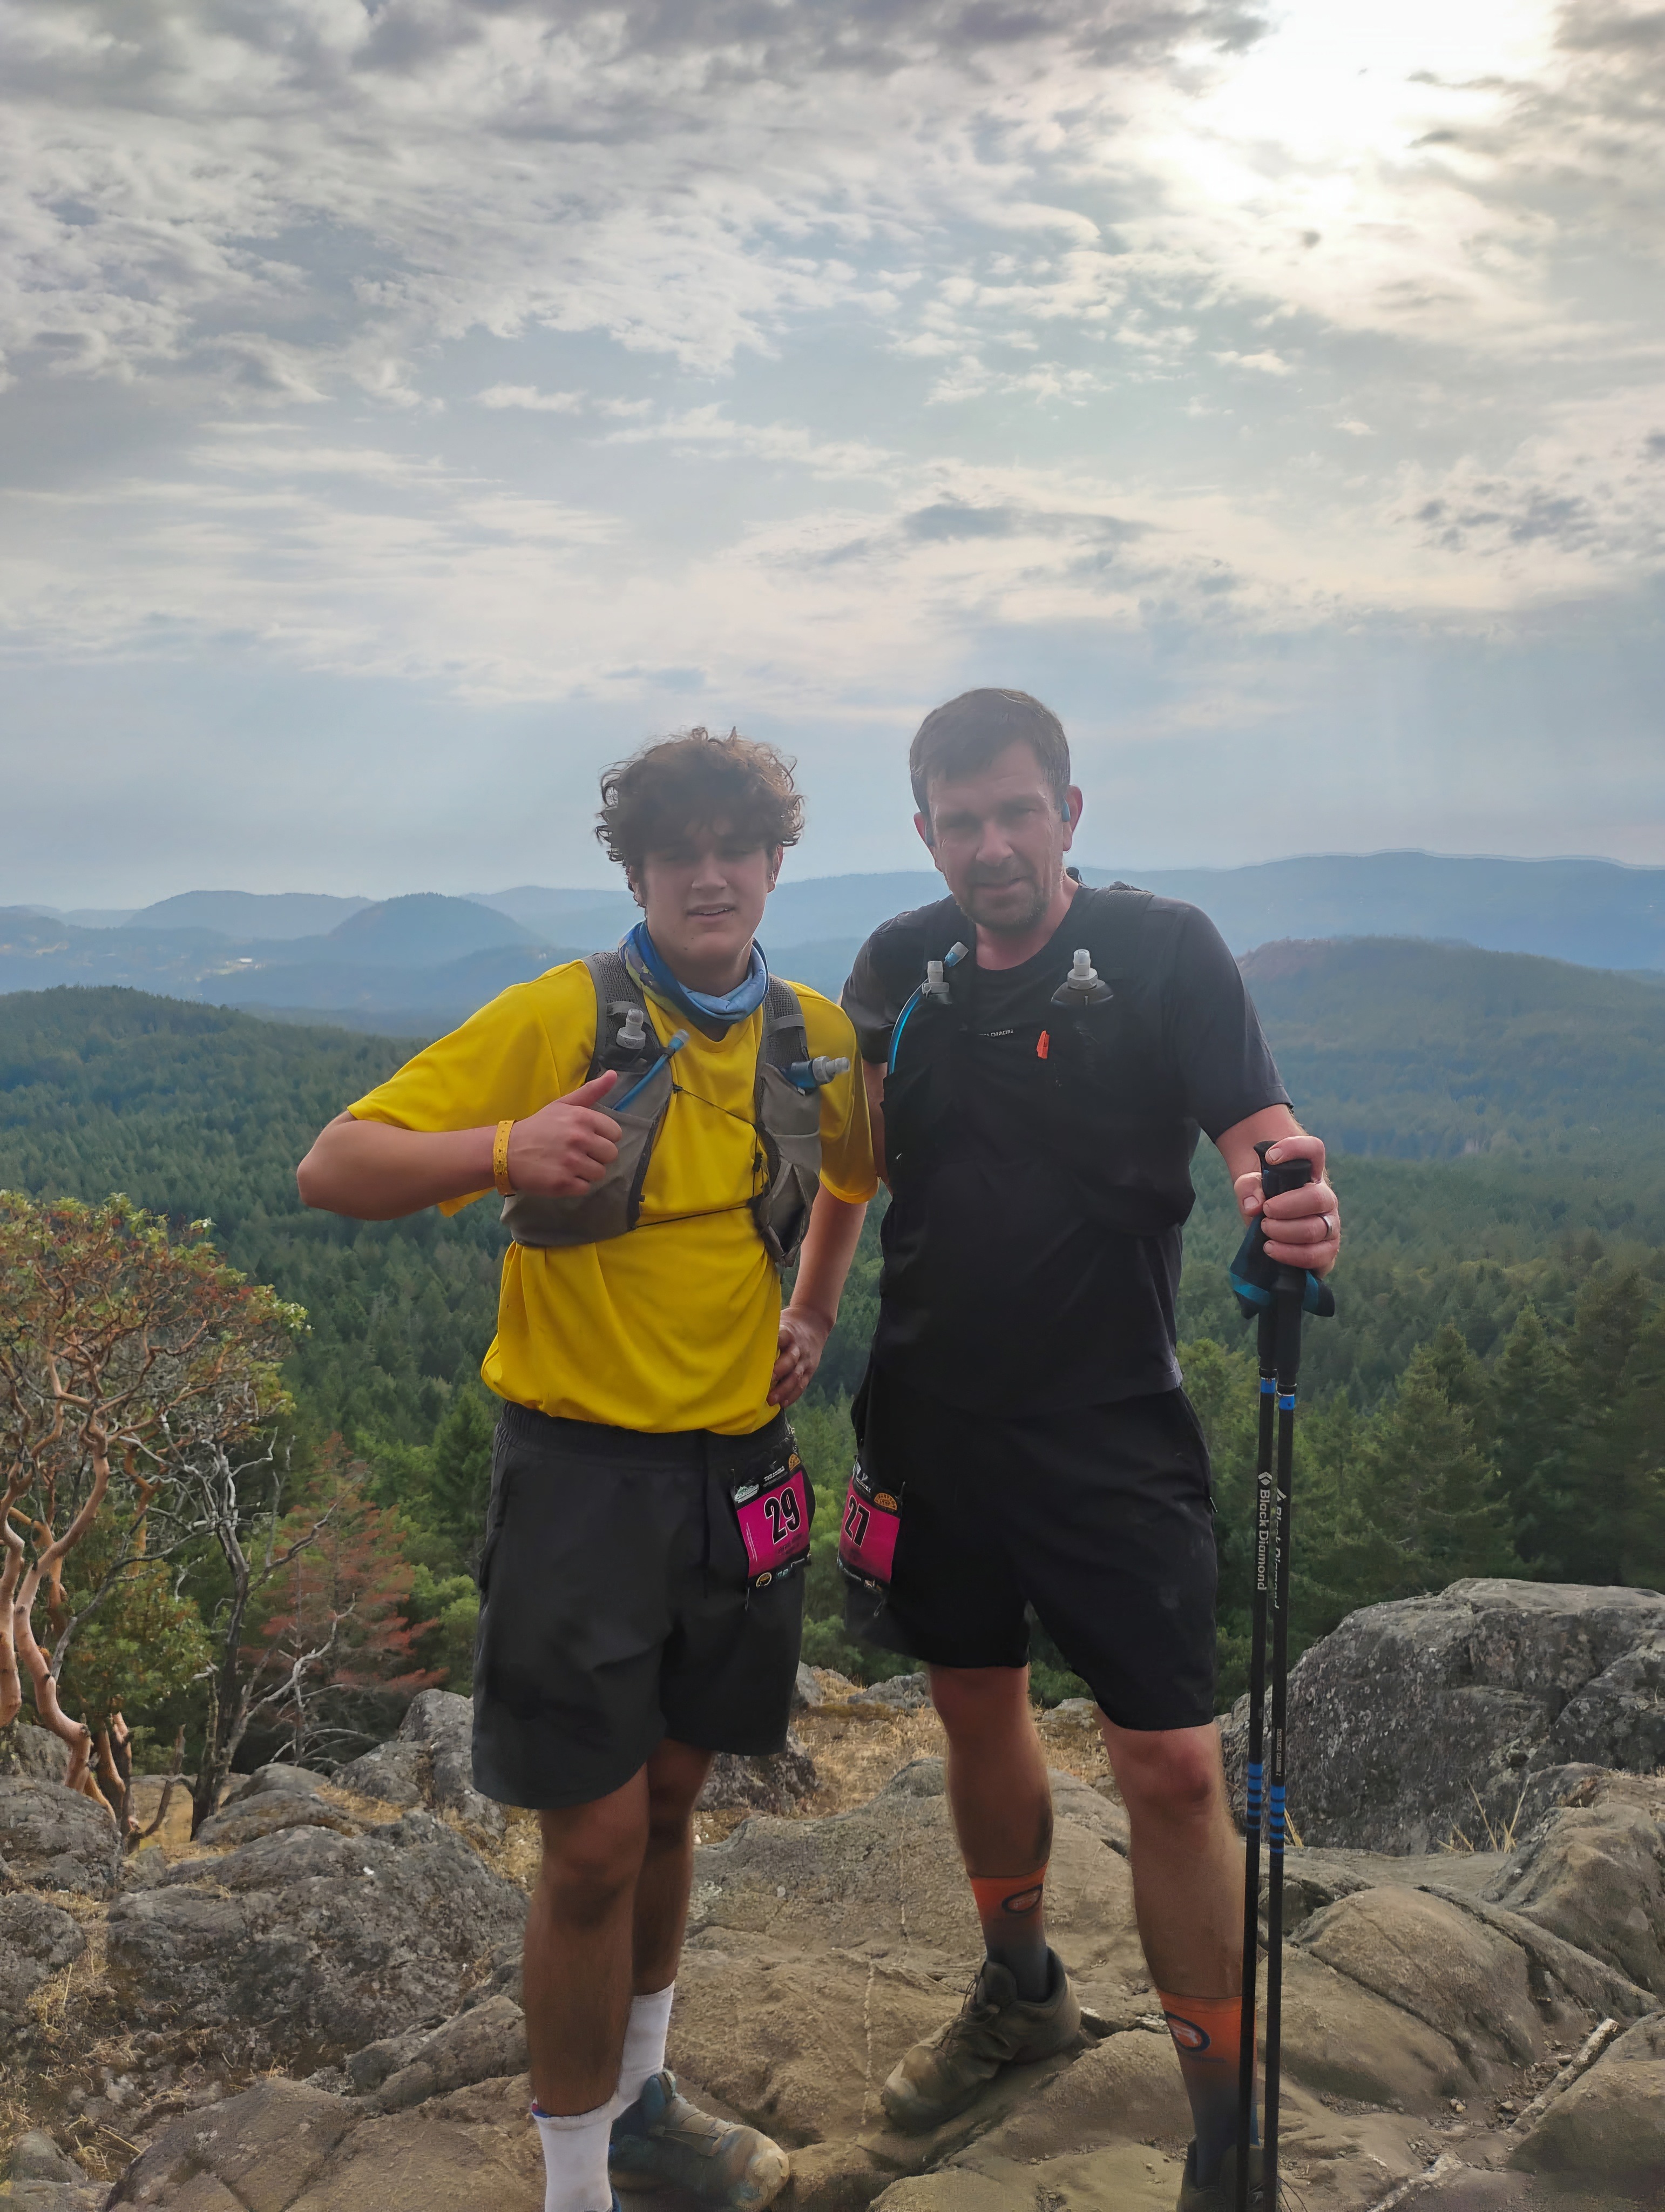
Doug and Marshall at the summit of Mt. Finlayson after completing the Finlayson Double this past weekend.
Footnotes And Sources
1. WSJ.com, September 18, 2026
2. Investing.com, September 18, 2026
3. CNBC.com, September 14, 2026
4. CNBC.com, September 15, 2026
5. WSJ.com, September 16, 2026
6. CNBC.com, September 17, 2026
7. CNBC.com, September 18, 2026
8. WSJ.com, September 16, 2026
9. WSJ.com, September 16, 2026
10. creatoreconomy.so, June 25, 2025
11. ideas.ted.com, November 18, 2025
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost.
The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice.
The market indexes discussed are unmanaged, and generally, considered representative of their respective markets. Index performance is not indicative of the past performance of a particular investment. Indexes do not incur management fees, costs, and expenses. Individuals cannot directly invest in unmanaged indexes. Past performance does not guarantee future results.
The Dow Jones Industrial Average is an unmanaged index that is generally considered representative of large-capitalization companies on the U.S. stock market. The Nasdaq Composite is an index of the common stocks and similar securities listed on the Nasdaq stock market and considered a broad indicator of the performance of stocks of technology and growth companies. The MSCI EAFE Index was created by Morgan Stanley Capital International (MSCI) and serves as a benchmark of the performance of major international equity markets, as represented by 21 major MSCI indexes from Europe, Australia, and Southeast Asia. The S&P 500 Composite Index is an unmanaged group of securities that are considered to be representative of the stock market in general.
U.S. Treasury Notes are guaranteed by the federal government as to the timely payment of principal and interest. However, if you sell a Treasury Note prior to maturity, it may be worth more or less than the original price paid. Fixed income investments are subject to various risks including changes in interest rates, credit quality, inflation risk, market valuations, prepayments, corporate events, tax ramifications and other factors.
International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.
Please consult your financial professional for additional information.