


Higher Bond Yields, Slower Job Growth and Another Mixed Week for Markets
Week Ending October 2, 2026
Markets finished last week mixed as investors tried to make sense of an economy that continues to send some pretty conflicting signals.
On one hand, the U.S. economy appears to be holding up better than expected.
On the other, job growth slowed considerably in September.
Then we had bond yields moving higher again, oil prices remaining elevated and artificial intelligence continuing to support technology stocks.
If that sounds like a lot of different things pulling markets in different directions, it was.
And I think that is really the story right now.
The economy isn't clearly weakening.
Inflation isn't completely under control.
Interest rates remain an important part of the conversation.
And investors are still trying to figure out what all of that means for central banks over the next few months.
Market Overview
Weekly Market Performance
- S&P 500: -0.27%
- Nasdaq Composite: +0.45%
- Dow Jones Industrial Average: -1.26%
- MSCI EAFE Index: -1.81%
- S&P/TSX Composite Index: -0.83%
It was another mixed week across the major markets.
The Nasdaq managed to finish higher, helped once again by strength in technology and AI related companies.
The S&P 500 finished slightly lower, while the Dow had a more difficult week, falling 1.26%.
Here at home, the S&P/TSX Composite finished the week down approximately 0.8%. The TSX actually had a strong Friday, gaining nearly 1%, but that wasn't quite enough to make up for losses earlier in the week.
Bond Yields Are Back in the Spotlight
One of the biggest stories last week was the bond market.
The yield on the 10 year U.S. Treasury climbed above 5.2%, reaching levels we haven't seen in many years.
We've talked about bond yields quite a bit lately, but they are important because they affect so many different parts of the economy.
Higher yields can mean higher borrowing costs for businesses.
They can influence mortgage rates.
They can make bonds more attractive compared with stocks.
And they can put pressure on the valuations investors are willing to pay for companies.
That last point is particularly important for technology companies, where investors are often paying today based on profits they expect many years into the future.
So when yields move higher quickly, it can make for some uncomfortable days in the stock market.
But that doesn't necessarily mean there is something fundamentally wrong with the economy.
It means investors are adjusting to a world where borrowing costs may stay higher for longer than they originally expected.
The Economy Is Sending Mixed Messages
This is where things get interesting.
The latest revision to second quarter U.S. GDP showed the economy grew at an annualized rate of 2.2%, up from the previous estimate of 1.5%.
That's a fairly meaningful revision.
It tells us the economy was stronger during the spring than we initially thought.
Normally, stronger economic growth would be good news.
And for the most part, it is.
But markets are in one of those periods where good economic news can also create questions about interest rates.
If the economy remains strong, the Federal Reserve has less reason to lower rates and potentially more reason to keep rates higher.
Then Friday's employment report gave investors a very different message.
The U.S. economy added just 29,000 jobs in September, well below the 133,000 jobs added in August after revisions.
July's numbers were also revised lower.
That suggests the labour market may finally be cooling.
And that matters because a softer labour market could reduce some of the pressure on the Federal Reserve to continue raising interest rates.
Markets reacted positively on Friday, particularly technology stocks, as investors lowered their expectations for another Fed increase later this month.
Inflation Still Isn't Quite Where the Fed Wants It
We also received another important inflation update.
The Personal Consumption Expenditures Index, or PCE, showed inflation running at 3.4% compared with a year ago.
PCE is worth paying attention to because it is one of the Federal Reserve's preferred measures of inflation.
The Fed's long term inflation target remains 2%.
So we aren't there yet.
This is really the balancing act central banks continue to face.
Raise rates too much and you risk slowing the economy unnecessarily.
Do too little and inflation could remain above target for longer.
It's a difficult line to walk, particularly when the economic data keeps telling slightly different stories.
AI Continues to Support Technology
And then, of course, we have artificial intelligence.
We've talked about AI quite a bit this year, and it continues to be one of the strongest themes in the market.
Semiconductor stocks helped markets during the week, and technology stocks rallied again on Friday, helping the Nasdaq finish the week higher and reach a new intraday record.
There is clearly enormous investment going into AI infrastructure.
But I continue to think investors need to keep some perspective here
AI can be an incredibly important long term investment theme without every AI related company being a good investment at every price.
Those are two very different things.
As more money flows into the space, investors are going to become increasingly focused on which companies can actually turn all of this spending into sustainable profits.
What About Canada?
Canada had its own interesting week.
The S&P/TSX Composite finished at 35,502.65 on Friday, down approximately 0.83% for the week. Friday itself was much stronger, with the index gaining 0.99%, led by materials and industrial companies.
But I think the more important Canadian story came from the economy.
Statistics Canada reported that Canadian GDP was essentially unchanged in July.
That followed a much stronger second quarter, so the July numbers suggest some of that momentum may be starting to cool.
There were still pockets of strength.
Construction increased 1.3% in July, marking its fourth consecutive monthly increase, and utilities were also stronger.
But manufacturing declined, along with mining, quarrying and oil and gas extraction. Overall, only 10 of Canada's 20 major industrial sectors expanded during the month.
This matters because the Bank of Canada is dealing with a slightly different problem than the Federal Reserve.
The Bank of Canada is currently holding its policy rate at 2.25%.
Canadian economic growth remains somewhat uneven, while inflation has been hovering around 3%, partly because of higher gasoline prices.
At the same time, ongoing trade tensions with the United States are creating another layer of uncertainty for Canadian businesses and the economy.
So the Bank of Canada has to balance slower areas of the economy against inflation that is still above its 2% target.
Sound familiar?
Central banking isn't particularly easy right now on either side of the border.
What Does This Mean for Investors?
Weeks like this are a good reminder that markets don't move based on one piece of information.
We had stronger economic growth.
Then weaker job growth.
Inflation is still above target.
Bond yields moved higher.
Technology stocks rallied.
And the TSX finished lower despite a strong Friday.
If you're trying to make investment decisions based on each new headline, it can become exhausting pretty quickly.
And more importantly, it usually isn't necessary.
For most long term investors, whether the Federal Reserve raises rates one more time this year shouldn't change the financial plan.
Neither should one disappointing jobs report.
What matters much more is whether your portfolio is properly diversified, whether you're taking the appropriate amount of risk and whether your investments are still aligned with what the money is actually there to accomplish.
That's the part we can control.
What the Week Really Meant
If I had to summarize last week, I would say investors are still trying to answer a question we've been asking for quite some time:
How much can the economy slow without actually tipping into something more serious?
So far, the answer remains unclear.
Economic growth has been stronger than expected.
But job growth is slowing.
Inflation is still above target.
Bond yields remain elevated.
And here in Canada, economic growth was essentially flat in July.
There are reasons to be cautious.
There are also reasons to remain optimistic.
And that combination is probably going to create some volatility along the way.
But volatility doesn't mean our plan isn't working.
It means markets are doing what markets have always done.
They absorb new information.
They adjust expectations.
They move up.
They move down.
And over time, successful investing has much more to do with staying disciplined through those periods than predicting every one of them correctly.
Our financial plans aren't built around knowing exactly what the Federal Reserve or Bank of Canada will do next.
They're built around your retirement.
Your income needs.
Your family.
Your goals.
And making sure your money continues working toward the things that actually matter to you.
Looking Ahead
The coming week is a little quieter, but there are still a few things worth watching.
In the U.S., investors will get new information on the services sector, international trade, consumer credit and consumer sentiment.
We will also get minutes from the Federal Reserve's September meeting, which could give investors more insight into how Fed officials are thinking about inflation and interest rates after their most recent rate increase.
Here in Canada, we will get August trade data on Tuesday.
But the bigger Canadian report comes Friday with September's Labour Force Survey.
That will give us a fresh look at employment and unemployment across Canada after the economy lost approximately 42,000 jobs in August.
With the Bank of Canada's next interest rate decision scheduled for October 28, employment, inflation and economic growth will all be important pieces of the puzzle.
And, as always, bond yields will be worth watching.
If yields continue moving higher, we could see some additional pressure on stocks.
If they settle down, markets may get a little breathing room.
This Week: Key Economic Data
Monday, October 5
- U.S. Services Purchasing Managers Index
- U.S. ISM Services Index
Tuesday, October 6
- U.S. Trade Balance
- Canadian Merchandise Trade Balance
Wednesday, October 7
- Federal Open Market Committee Meeting Minutes
- U.S. Consumer Credit
Thursday, October 8
- Weekly Jobless Claims
- U.S. Wholesale Trade
Friday, October 9
- Canadian Labour Force Survey
- U.S. Consumer Sentiment
This Week: Companies Reporting Earnings
Thursday, October 8
- PepsiCo
Friday, October 9
- Delta Air Lines
"You gain strength, courage, and confidence by every experience in which you really stop to look fear in the face."
– Eleanor Roosevelt
Simply talk about it, and you will break it. What is it?
Last Week's Riddle: They are captured by mud and snow, left behind but never taken, and rarely seen in isolation. What are they?
Answer: Footprints
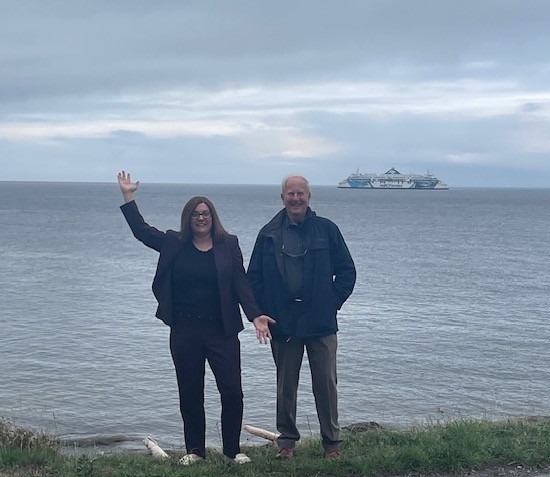
David showing Joanne around Gabriola Island ahead of seeing clients!
Footnotes And Sources
1. WSJ.com, October 2, 2026
2. Investing.com, October 2, 2026
3. CNBC.com, September 28, 2026
4. CNBC.com, September 29, 2026
5. WSJ.com, September 30, 2026
6. CNBC.com, October 1, 2026
7. WSJ.com, October 2, 2026
8. WSJ.com, September 30, 2026
9. WSJ.com, October 2, 2026
10. BuzzFeed, October 15, 2025
11. CareerTrainer.ai, July 21, 2026
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost.
The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice.
The market indexes discussed are unmanaged, and generally, considered representative of their respective markets. Index performance is not indicative of the past performance of a particular investment. Indexes do not incur management fees, costs, and expenses. Individuals cannot directly invest in unmanaged indexes. Past performance does not guarantee future results.
The Dow Jones Industrial Average is an unmanaged index that is generally considered representative of large-capitalization companies on the U.S. stock market. The Nasdaq Composite is an index of the common stocks and similar securities listed on the Nasdaq stock market and considered a broad indicator of the performance of stocks of technology and growth companies. The MSCI EAFE Index was created by Morgan Stanley Capital International (MSCI) and serves as a benchmark of the performance of major international equity markets, as represented by 21 major MSCI indexes from Europe, Australia, and Southeast Asia. The S&P 500 Composite Index is an unmanaged group of securities that are considered to be representative of the stock market in general.
U.S. Treasury Notes are guaranteed by the federal government as to the timely payment of principal and interest. However, if you sell a Treasury Note prior to maturity, it may be worth more or less than the original price paid. Fixed income investments are subject to various risks including changes in interest rates, credit quality, inflation risk, market valuations, prepayments, corporate events, tax ramifications and other factors.
International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.
Please consult your financial professional for additional information.