


Election Clarity, AI Volatility and a Better Finish to a Difficult Week
Week Ending November 6, 2026
Hello everyone!
Markets had plenty to keep investors on their toes this week. It was an unusually volatile few days, particularly for technology stocks. Investors were digesting the U.S. midterm elections, continuing to question some of the very high valuations surrounding artificial intelligence, and watching the latest economic data.
There were some significant swings along the way, but I think the week provided a useful reminder that sometimes the day to day movement in markets can look much more dramatic than the bigger picture.
Let’s take a closer look.
Market Overview
Weekly Market Performance
- S&P 500: −2.68%
- Nasdaq Composite: −3.37%
- Dow Jones Industrial Average: −0.94%
- MSCI EAFE Index: −1.95%
- S&P/TSX Composite Index: +0.47%
Technology was once again at the centre of the weakness south of the border. Investors continued reducing exposure to some of the companies most closely associated with the AI investment boom. The Nasdaq, which has much heavier technology exposure, experienced the largest decline of the major U.S. indexes.
There was also tremendous volatility underneath those weekly numbers. Markets rallied sharply following the U.S. midterm elections before renewed concerns about technology valuations reversed much of that enthusiasm later in the week.
Stocks recovered somewhat on Friday, but it was quite a journey for five trading days.
AI Had Another Reality Check
I’ve talked quite a bit this year about artificial intelligence, and I still believe it will remain one of the major investment and economic themes for years to come.
But there is an important distinction between believing in a technology and believing that every company connected to that technology is worth any price.
That distinction seemed to matter this week.
Investors have become increasingly focused on the enormous amounts of money being spent on data centres, chips and AI infrastructure, and on how quickly those investments can ultimately translate into higher profits.
I actually think that is a healthy conversation for markets to have.
When expectations become extremely high, even very good corporate results can disappoint investors. A company doesn’t necessarily have to do badly for its share price to fall. Sometimes it simply has to do less spectacularly than the market expected.
This doesn’t mean the AI story is suddenly over.
The more interesting question is how the story evolves from here. Investors are increasingly asking companies to demonstrate that the billions being invested in AI can eventually generate meaningful revenue, productivity improvements and profits.
That is a much higher bar than simply announcing another AI initiative.
Politics Created Some Big Swings, but Fundamentals Still Matter
The U.S. midterm elections also played a role in this week’s volatility.
Markets initially responded positively as investors gained greater clarity about the political landscape.
From an investment perspective, I’m less interested in whether markets initially like or dislike an election result and much more interested in what happens afterward.
Investors will now be watching fiscal policy, taxes, regulation, trade and government spending. For Canadians, the U.S. trade relationship deserves particular attention because changes in American policy can eventually affect Canadian exporters, businesses and our dollar.
Political headlines can move markets quickly, but over longer periods corporate profits, economic growth, inflation and interest rates tend to matter much more.
That is why making major portfolio decisions based solely on an election result can be so difficult.
Friday Brought Some Relief
After a particularly difficult Thursday, markets recovered somewhat on Friday as investors digested the latest economic data.
Employment numbers are important because they sit right at the intersection of economic growth and interest rates.
A reasonably healthy labour market supports consumer spending and reduces immediate recession concerns. But if the economy remains too strong and inflation stays elevated, central banks have less reason to lower interest rates.
That push and pull is going to remain important.
Markets would obviously like strong growth, falling inflation and lower interest rates all at once. The economy rarely gives investors such a perfect combination.
What About Canada?
Canada was actually one of the brighter spots this week.
The S&P/TSX Composite gained approximately 0.47%, rising from 35,620.03 on Friday, October 30th to 35,789.09 on Friday, November 6th.
That means Canada outperformed all four of the other major markets we follow this week.
There is a good reason Canadian and U.S. markets can behave very differently.
The U.S. market, particularly the Nasdaq and S&P 500, has significant exposure to large technology companies. Canada’s market looks quite different. Financials, energy and materials have a much greater influence on the TSX.
So when technology shares experience a sharp correction, the Canadian market does not necessarily experience the same degree of pressure.
This week, Canada’s different sector composition helped the market hold up considerably better while U.S. technology stocks came under pressure.
Ottawa’s Budget Is Part of the Picture Too
Here at home, investors were also digesting the federal budget.
For markets, the important question isn’t simply how much the government plans to spend. It is where that money goes, how it is financed, and whether the spending ultimately improves Canada’s productive capacity and economic growth.
For investors, increased government spending can create opportunities in areas such as infrastructure, housing, defence and Canadian businesses that benefit from new investment. At the same time, larger deficits and additional government borrowing matter because they can influence the bond market, interest rates and eventually the Canadian dollar.
That creates an interesting balancing act for Canada.
If government investment helps improve productivity and encourages private sector investment, that could support longer term economic growth. But if fiscal spending adds demand to the economy without increasing productive capacity, it can make the inflation and interest rate picture more complicated.
That is something I’ll be watching closely, particularly alongside the Bank of Canada. Fiscal policy and monetary policy do not operate independently. What Ottawa does with spending and borrowing can ultimately affect the economic environment the Bank of Canada is trying to manage.
Oil also remains an important economic variable for Canada.
Lower energy costs can help households and potentially take some pressure off inflation, but energy companies are also an important part of the Canadian stock market and Canadian economy.
What may be positive for consumers, therefore, isn’t necessarily positive for every part of the TSX.
The bigger message for me is that Canada and the United States do not own the same stock market.
That sounds obvious, but it is easy to forget when almost every financial headline focuses on the S&P 500 or Nasdaq.
What Does This Mean for Investors?
Weeks like this can make investing feel much more dramatic than it really needs to be.
Think about what happened in only a few days. Investors moved money away from technology, reacted to an election, experienced a significant rally, endured a very difficult session and then watched stocks recover somewhat again on Friday.
Trying to trade around all of those moves would have required getting several decisions right in succession.
That’s a difficult way to build long term wealth.
There is another lesson here too.
Diversification doesn’t mean everything you own goes up at the same time. In fact, the whole point is that it shouldn’t.
The Nasdaq fell 3.37% this week while the TSX gained approximately 0.47%.
Different investments respond differently to technology valuations, interest rates, economic growth, currencies and commodity prices.That doesn’t eliminate volatility, but it can help prevent a portfolio from becoming dependent on one company, one sector or one economic outcome.
What the Week Really Meant
I think the most important lesson this week is that a great long term investment theme can still experience very difficult short term periods.
Artificial intelligence may continue changing the economy, but that doesn’t mean AI related share prices can only move higher.
Politics can create short bursts of volatility, but elections themselves don’t determine the ultimate success of a retirement plan.
And a sharp move in the Nasdaq on a Thursday doesn’t suddenly change how much income a family needs in retirement, when somebody plans to retire, or what they would like to leave to their children.
Those are the things we ultimately build portfolios around.
Markets will always give us something new to worry about. A good financial plan gives us a framework for deciding which worries actually require us to do something.
Most of the time, patience and perspective are far more valuable than reacting to every headline.
Looking Ahead
Inflation returns to centre stage this coming week.
Investors will be watching both consumer and producer inflation closely for clues about whether price pressures are continuing to moderate.
That matters because inflation remains one of the biggest influences on the path of interest rates.
We will also get additional information on small business optimism, household debt and credit, weekly jobless claims and the housing market.
For Canadian investors, I’ll continue watching the TSX, energy and commodity prices, the Canadian dollar, the implications of the federal budget and how expectations for interest rates evolve.
One week rarely changes the economic picture completely, but taken together these pieces help us understand where the economy may be heading.
This Week: Key Economic Data
Monday, November 9th
- U.S. Wholesale Trade
- Federal Reserve speakers
Tuesday, November 10th
- U.S. Consumer Price Index
- NFIB Small Business Optimism Index
- New York Fed Q3 Household Debt & Credit report
- Federal Reserve speakers
Thursday, November 12th
- U.S. Weekly Jobless Claims
- U.S. Existing Home Sales
- U.S. Treasury Balance
- Federal Reserve speakers
Friday, November 13th
- U.S. Producer Price Index
- Federal Reserve speaker
This Week: Companies Reporting Earnings
Monday, November 9th
- Constellation Energy
- KKR
Thursday, November 12th
- Cisco Systems
- Applied Materials
Companies may change their reporting dates without notice.
“Change happens by listening and then starting a dialogue with the people who are doing something you don’t believe is right.”
– Jane Goodall
It grows down, yet it also grows up. What is it?
Last Week's Riddle: You throw it out when you need to use it. You bring it up when you don’t. As you travel, it goes with you. What is it?
Answer: An anchor.
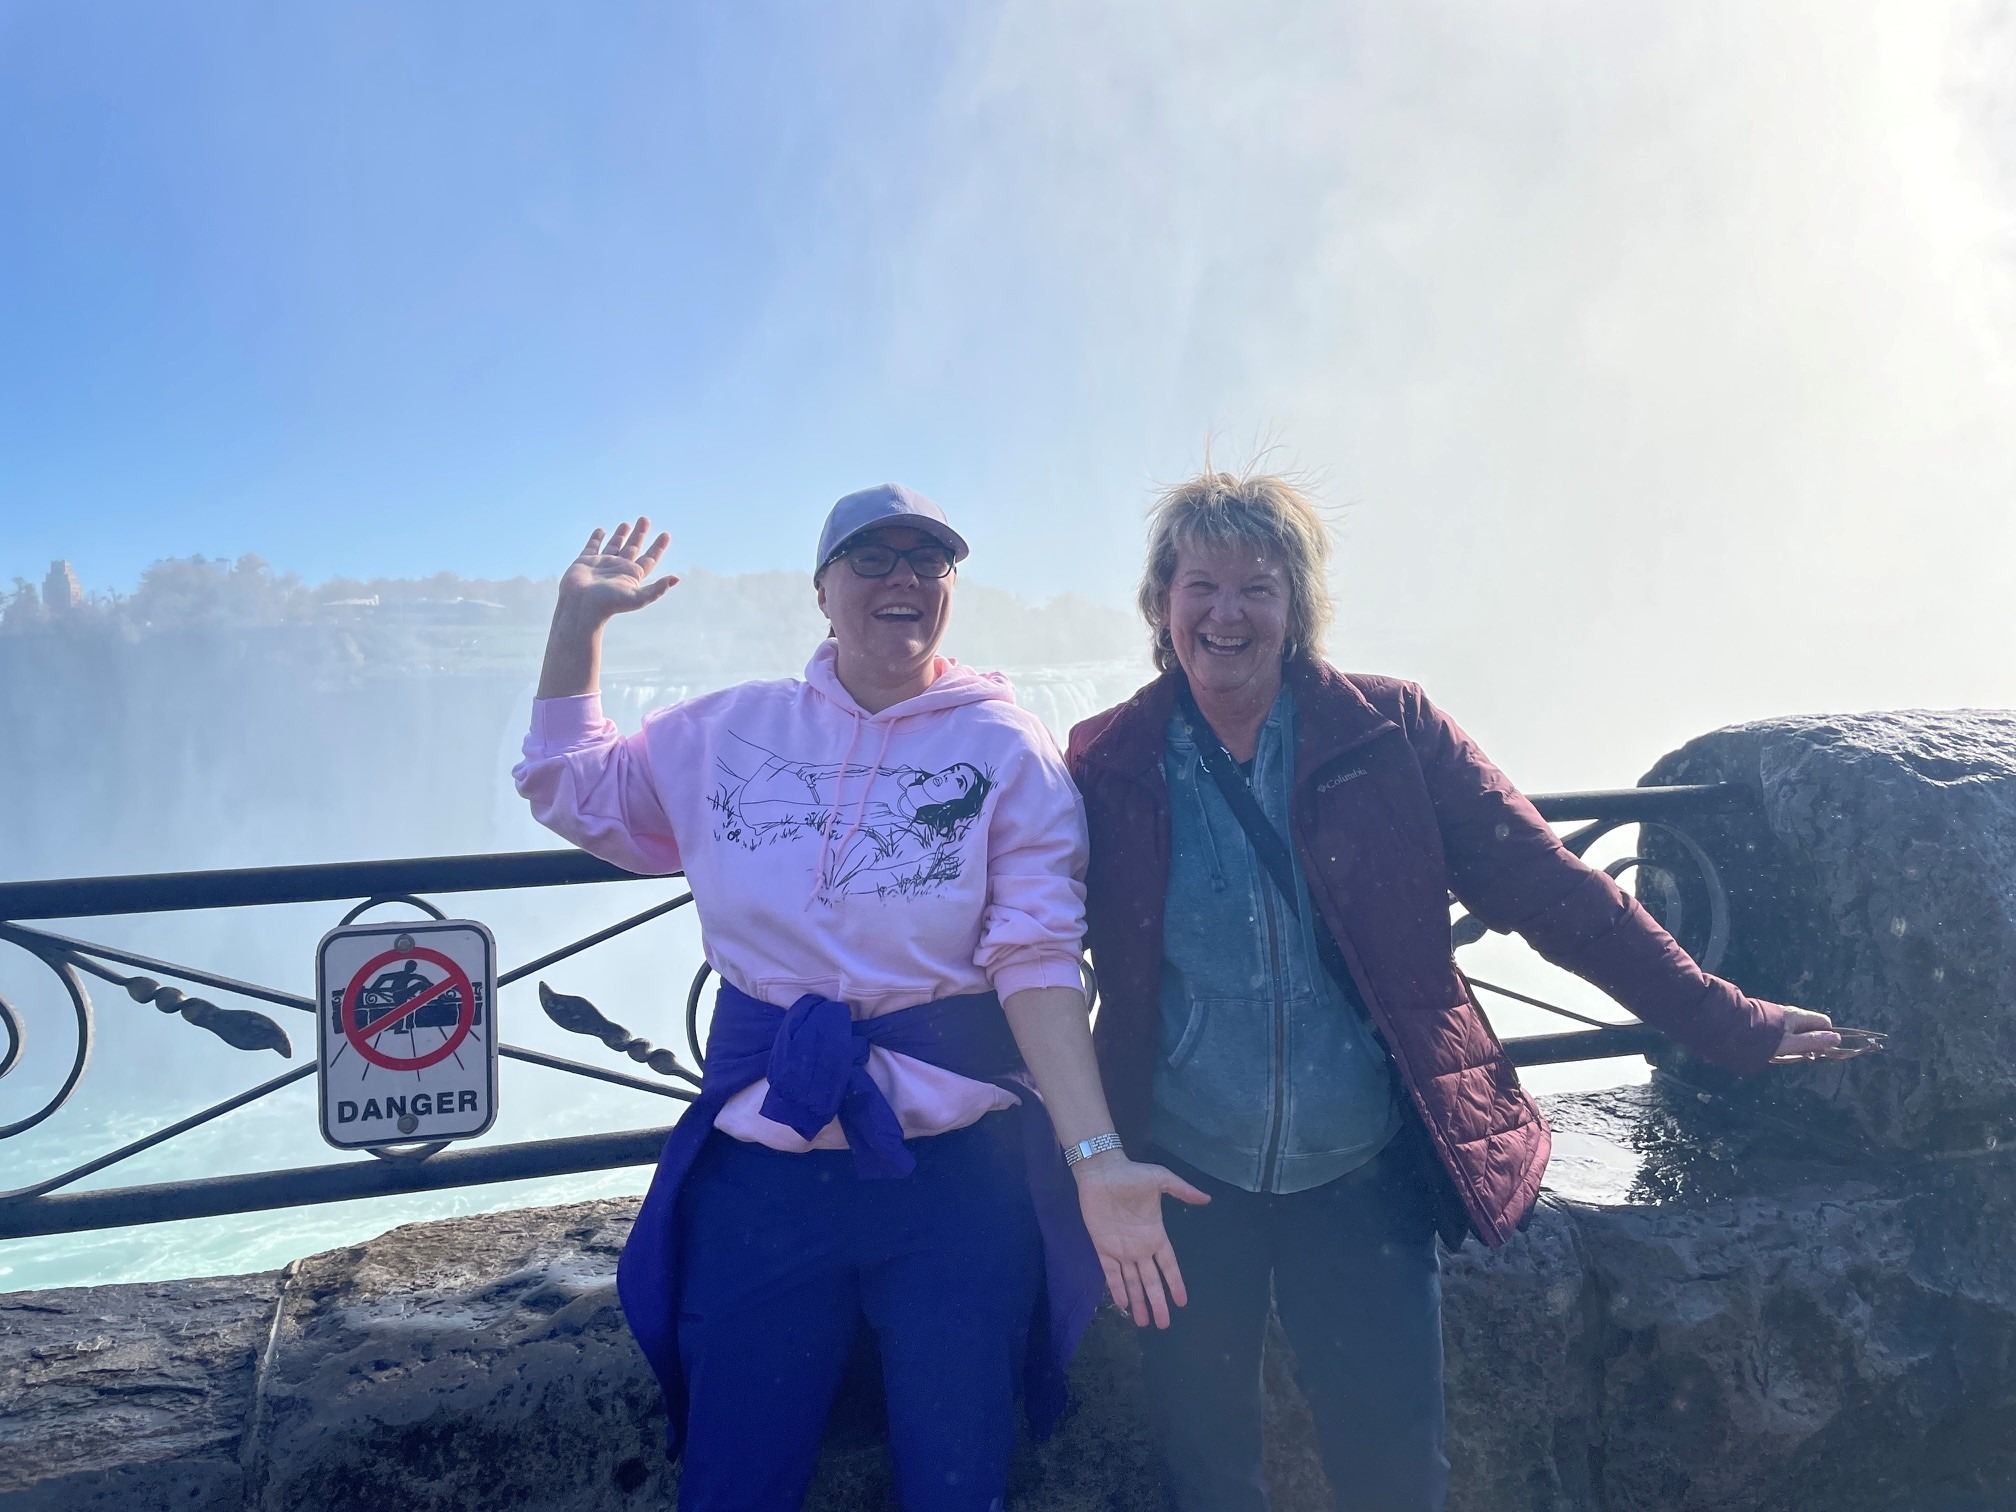
Feeling the mist at Niagara Falls! A little sightseeing between client visits during our Ontario trip. Shirley and I may have underestimated just how much “mist” there would be!
Footnotes And Sources
1. WSJ.com, November 6, 2026
2. Investing.com, November 6, 2026
3. CNBC.com, November 2, 2026
4. CNBC.com, November 3, 2026
5. WSJ.com, November 4, 2026
6. CNBC.com, November 5, 2026
7. CNBC.com, November 6, 2026
8. WSJ.com, November 4, 2026
9. Healthline, April 14, 2026
10.American Psychological Association, July 21, 2026
Investing involves risks, and investment decisions should be based on your own goals, time horizon, and tolerance for risk. The return and principal value of investments will fluctuate as market conditions change. When sold, investments may be worth more or less than their original cost.
The forecasts or forward-looking statements are based on assumptions, may not materialize, and are subject to revision without notice.
The market indexes discussed are unmanaged, and generally, considered representative of their respective markets. Index performance is not indicative of the past performance of a particular investment. Indexes do not incur management fees, costs, and expenses. Individuals cannot directly invest in unmanaged indexes. Past performance does not guarantee future results.
The Dow Jones Industrial Average is an unmanaged index that is generally considered representative of large-capitalization companies on the U.S. stock market. The Nasdaq Composite is an index of the common stocks and similar securities listed on the Nasdaq stock market and considered a broad indicator of the performance of stocks of technology and growth companies. The MSCI EAFE Index was created by Morgan Stanley Capital International (MSCI) and serves as a benchmark of the performance of major international equity markets, as represented by 21 major MSCI indexes from Europe, Australia, and Southeast Asia. The S&P 500 Composite Index is an unmanaged group of securities that are considered to be representative of the stock market in general.
U.S. Treasury Notes are guaranteed by the federal government as to the timely payment of principal and interest. However, if you sell a Treasury Note prior to maturity, it may be worth more or less than the original price paid. Fixed income investments are subject to various risks including changes in interest rates, credit quality, inflation risk, market valuations, prepayments, corporate events, tax ramifications and other factors.
International investments carry additional risks, which include differences in financial reporting standards, currency exchange rates, political risks unique to a specific country, foreign taxes and regulations, and the potential for illiquid markets. These factors may result in greater share price volatility.
Please consult your financial professional for additional information.